
Latest Financial Results Summary
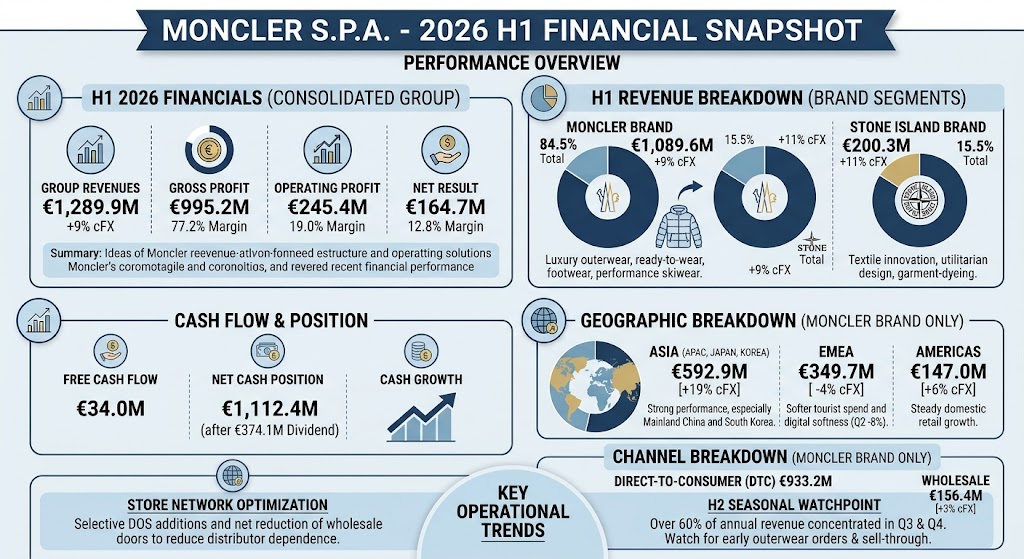
Moncler S.p.A. reported its financial results for the first half of 2026(H1 2026) and the second quarter of 2026(Q2 2026). Consolidated Group revenues for H1 2026 reached €1,289.9 million, representing an increase of 9% at constant exchange rates(cFX) and 5% at current exchange rates compared to €1,225.7 million in H1 2025. For Q2 2026, Group revenue reached €409.3 million, up 5% cFX year-over-year. Gross profit for H1 2026 totaled €995.2 million, expanding the gross margin to 77.2% compared to 76.9% in H1 2025. Operating profit(EBIT) rose to €245.4 million with an EBIT margin of 19.0%(up from €224.8 million and an 18.3% margin in H1 2025). Group net result reached €164.7 million(12.8% net margin), up 7% from €153.5 million in H1 2025. Free cash flow improved to €34.0 million compared to €15.0 million in H1 2025, and the net cash position stood at €1,112.4 million as of June 30, 2026, following €374.1 million in dividend distributions.
Segment and Regional Revenue Breakdown
Brand Segments
- Moncler Brand: Generated revenues of €1,089.6 million in H1 2026, accounting for 84.5% of total consolidated revenues, growing 9% cFX YoY(Q2 revenues were €323.1 million, up 3% cFX). Moncler specializes in luxury outerwear, high-end lifestyle ready-to-wear, footwear, and accessories, anchored by its signature down jackets and performance skiwear collections such as Moncler Grenoble.
- Stone Island Brand: Generated revenues of €200.3 million in H1 2026, accounting for 15.5% of total consolidated revenues, up 11% cFX YoY(Q2 revenues were €86.3 million, up 11% cFX). Stone Island is an Italian sportswear brand centered on textile innovation, utilitarian design, and specialized garment-dyeing technologies.
Channel Breakdown(Moncler Brand)
- Direct-to-Consumer(DTC): Reached €933.2 million, representing 85.6% of Moncler brand revenue, up 10% cFX YoY with a comparable store sales growth(CSSG) of +7%.
- Wholesale: Reached €156.4 million, representing 14.4% of Moncler brand revenue, up 3% cFX YoY.
Geographic Breakdown(Moncler Brand)
- Asia(APAC, Japan, Korea): Accounted for €592.9 million, representing 54.4% of Moncler brand revenues, up 19% cFX YoY. In Q2, regional revenues grew 12% cFX, led by strong performance in Mainland China and South Korea.
- EMEA: Accounted for €349.7 million, representing 32.1% of Moncler brand revenues, declining 4% cFX YoY. In Q2, EMEA revenues contracted 8% cFX due to softer tourist spending and digital channel softness.
- Americas: Accounted for €147.0 million, representing 13.5% of Moncler brand revenues, up 6% cFX YoY. In Q2, the Americas grew 4% cFX, supported by steady domestic retail consumption.
Operational Changes, Next Quarter Watchpoints, and Outlook
Store Closures and Distribution Network Changes
During Q2 2026, the Group continued its selective network optimization. For the Moncler brand, directly operated stores(DOS) stood at 298 units as of June 30, 2026, reflecting a net increase of 3 stores from 295 units at March 31, 2026(including additions such as the Sydney Chatswood boutique and a store relocation in Geneva). Concurrently, Moncler mono-brand wholesale doors decreased by a net of 3 units during the quarter(from 47 down to 44 doors). Across both brands, wholesale rationalization remains an active strategy to reduce third-party distributor dependence, eliminate markdown dilution, and prioritize direct brand control.
Next Quarter Watchpoints
- H2 Seasonal Leverage: Moncler operates with heavy second-half seasonality, where Q3 and especially Q4 historically generate over 60% of annual revenue and the vast majority of operating profits. Inventory sell-through rates and early outerwear orders will serve as the primary indicator for full-year operating margin delivery.
- European Tourist Inflow Stabilization: Monitoring whether EMEA retail traffic recovers from the Q2 drop(-8% cFX) as global travel flows normalize.
- Stone Island DTC Expansion: Tracking whether the acceleration in Stone Island’s direct retail(+16% cFX in H1 2026) sustains its pace across newly converted global flagships.
Future Outlook
Management maintains an operational target of defending profitability toward an EBIT margin in the 29%+ region over the medium term. For full-year 2026, capital expenditures are guided at approximately 6% of consolidated revenues, primarily allocated to boutique expansions and supply chain infrastructure, while marketing expenses are targeted at around 7% of revenues.
Three-Month Share Price Performance and Drivers
Moncler S.p.A.(BIT: MONC) traded from approximately €53.80 in mid-June 2026 down to €43.60 as of September 10, 2026, reflecting a three-month decline of approximately 19%.
Market Drivers
- Luxury Sector Sentiment De-rating: Broader European luxury equities faced widespread valuation compression amid growing investor concern over slowing consumer discretionary demand and normalization of personal luxury spending.
- Deceleration in Europe and Tourist Spend: Despite continued double-digit resilience in Asian local markets, Moncler’s Q2 slowdown in EMEA(-8% cFX) prompted market analysts to trim second-half estimates.
- Foreign Exchange Headwinds: Significant currency fluctuations(with a 4-percentage-point drag between cFX and reported revenue growth in H1 2026) raised concerns regarding translational gross margin impacts heading into the peak winter sales cycle.
Sources
- https://www.monclergroup.com/v3/assets/blt61bda6b71f29a239/blt6651b04f18f67307/6a60e7584e8afd132530f0c6/Moncler-Group-Press-Release-H1-2026.pdf
- https://www.monclergroup.com/v3/assets/blt61bda6b71f29a239/blt2160e62b4837e0b2/6a60e63c64a87c79ce24edb6/Moncler-Group-H1-2026-Financial-Results-Presentation.pdf
- https://www.borsaitaliana.it/borsa/azioni/scheda/IT0004965148.html
Back to Moncler