
Latest Quarterly Financial Results Summary (Q2 2026)
Koninklijke KPN N.V. reported its second-quarter 2026 financial results, characterized by steady operational progress in broadband and mobile, counterbalanced by one-off base effects from the prior year:
- Adjusted Revenues:€1,464m, down 0.5% year-on-year.
- Group Service Revenues:€1,350m, up 0.8% year-on-year, supported by solid demand in Consumer (+1.9%), Small and Medium Enterprises (+6.9%), and Wholesale (+1.0%).
- Adjusted EBITDA AL:€668m, down 0.3% year-on-year on a reported basis.Excluding the absence of prior-year intellectual property rights (IPR) benefits and IPv4 sales, underlying adjusted EBITDA AL increased by 3.4% year-on-year.Adjusted EBITDA AL margin stood at 45.6% (+8 bps year-on-year).
- Operating Profit (EBIT):€339m, declining 6.8% year-on-year, driven by lower reported EBITDA and higher asset depreciation.
- Net Profit:€207m, decreasing 1.0% year-on-year.
- Capital Expenditures (Capex):€308m, up 3.6% year-on-year, primarily due to intra-year rollout phasing.
- Free Cash Flow (FCF):€228m, surging 27% year-on-year, driven by working capital phasing and reduced interest payments.
Segment and Geographic Revenue Breakdown
KPN classifies its operational revenue into Consumer, Business, Wholesale, and Non-service/Other activities.
Segment Breakdown (Based on Q2 2026 Adjusted Revenues of €1,464m):
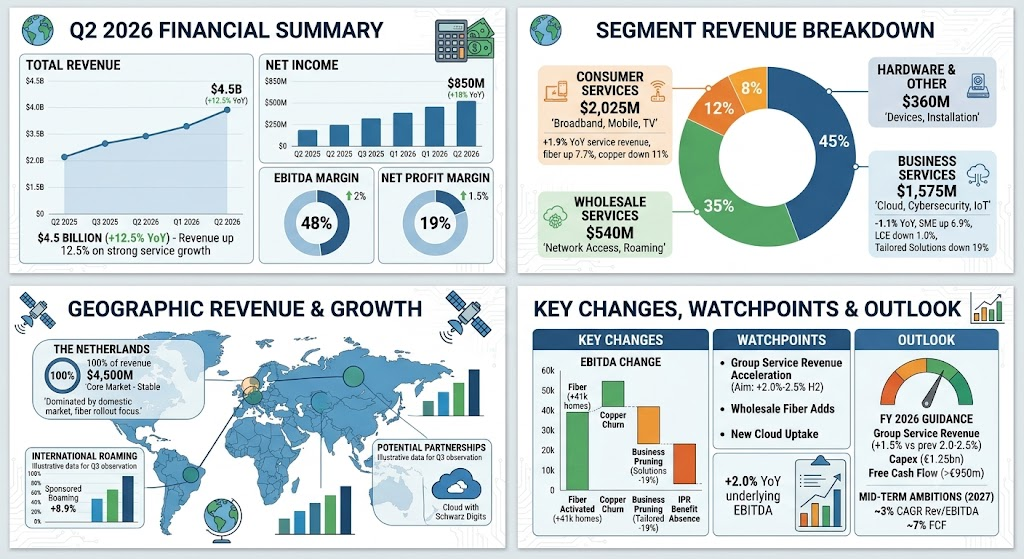
- Consumer Service Revenues (€711m, 48.6% of total revenue):Provides retail fixed broadband, interactive TV, fixed telephony, and mobile telecommunications to Dutch households.Fixed service revenue contributed €477m (+1.3% year-on-year), with fiber broadband growing 7.7% to €338m, offsetting copper declines (-11% to €130m).Mobile service revenue grew 3.2% to €234m.
- Business Service Revenues (€462m, 31.6% of total revenue):Delivers communication, connectivity, cybersecurity, cloud, and workspace solutions to enterprise customers.Total business service revenue slipped 1.1% year-on-year:
- SME: €207m (14.1% of total), growing 6.9% year-on-year.
- Large Corporate & Enterprise (LCE): €183m (12.5% of total), down 1.0% year-on-year.
- Tailored Solutions: €72m (4.9% of total), declining 19% year-on-year.
- Wholesale Service Revenues (€173m, 11.8% of total revenue): Provides open-access wholesale access to third-party operators for fixed network (fiber/copper) and mobile networks, as well as roaming solutions. Service revenue increased 1.0% year-on-year, led by international sponsored roaming (+8.9%).
- Non-Service Revenues & Other (€114m, 7.8% of total revenue):Comprises handset and hardware sales, installation services, and intellectual property/licensing fees.It declined 14% year-on-year due to high comparison hurdles from prior-year IPR settlements and IP address sales.
Geographic Breakdown:
- The Netherlands (~100% of revenue): KPN operates almost exclusively in the Dutch domestic market. International exposure is confined to cross-border roaming agreements, visitor roaming, and wholesale transit partnerships.The company’s strategic infrastructure deployment remains focused on Dutch national fiber coverage.
Key Changes, Next Quarter Watchpoints, and Future Outlook
Key Changes in the Current Quarter:
- Strategic Shift from Buildout to Fiber Monetization:KPN added 83,000 homes passed and activated 41,000 fiber homes in Q2 2026 (including Glaspoort), reaching a footprint of 5.966m homes passed and 2.834m activated homes.Over 70% of retail broadband customers are now on fiber, leading to a 7.7% expansion in fiber broadband revenue.
- Deliberate Margin Pruning in Tailored Solutions:The 19% drop in Tailored Solutions revenue reflects management’s ongoing initiative to exit low-margin, high-overhead custom contracts to preserve operating profitability.
- Regulatory Roadblock: The Dutch Authority for Consumers and Markets (ACM) prohibited Glaspoort’s planned acquisition/cooperation with Delta Fiber assets, restraining inorganic expansion in local fiber networks.
Next Quarter Watchpoints (Q3 2026):
- Service Revenue Acceleration:Management anticipates group service revenue growth to accelerate to approximately 2.0% to 2.5% year-on-year in H2 2026; Q3 performance will indicate whether enterprise migrations and consumer indexation increases are flowing through as planned.
- Wholesale Broadband Mix Migration: Observation of whether wholesale fiber customer additions can offset the churn in legacy copper lines (-21,000 broadband lines in wholesale during prior quarters).
- Cloud & Enterprise Partnerships:Market uptake of new strategic partnerships, such as the European sovereign cloud partnership with Schwarz Digits.
Future Outlook:
- Full-Year 2026 Guidance:
- Group service revenue growth revised to approximately +1.5% year-on-year (moderated from +2.0% to +2.5% previously) due to headwinds in Tailored Solutions and LCE.
- Adjusted EBITDA AL reaffirmed at approximately €2,670m.
- Capex reaffirmed at approximately €1.25bn.
- Free Cash Flow maintained at >€950m.
- Mid-Term Ambitions through 2027:Reconfirmed compound annual growth rates (CAGR) of ~3% for service revenues, ~3% for adjusted EBITDA AL, and ~7% for Free Cash Flow.
Past Three Months Stock Price Performance and Drivers
Stock Price Movement:
- Over the past three months (June 10, 2026 to September 8, 2026), KPN’s share price on Euronext Amsterdam (AMS: KPN) declined from €4.45 to €4.098, representing a total decrease of -7.91%.
Market Drivers Behind the Movement:
- Guidance Moderation on Top-Line Growth:Following the Q2 2026 earnings release on July 22, 2026, shares dropped as management trimmed full-year 2026 group service revenue growth expectations from 2.0%-2.5% to approximately 1.5%.Investors reacted cautiously to softening demand in large enterprise accounts and contract run-offs in Tailored Solutions.
- ACM Regulatory Headwind on Fiber Consolidation: Sentiment softened after the Dutch competition regulator blocked Glaspoort’s transaction involving Delta Fiber, dampening market expectations for near-term network consolidation synergies.
- Competitive Pricing Pressures: Intensified promotional activity from domestic competitors (such as VodafoneZiggo and Odido) in fixed broadband prompted concern regarding customer acquisition costs and churn rates.
Sources
- https://s202.q4cdn.com/886546970/files/doc_financials/2026/q2/KPN-Q2-2026-Press-release.pdf
- https://ir.kpn.com/results-and-reports/quarterly-results/
- https://telecomlead.com/5g/kpn-q2-2026-results-revenue-drops-0-5-fiber-revenue-rises-7-7-fiber-connections-reach-4-74-mn-126884
- https://www.investing.com/news/company-news/kpn-q2-2026-slides-solid-growth-masked-by-onetime-headwinds-93CH-4805795
- https://quartr.com/companies/koninklijke-kpn-n-v_12948
Back to KPN