
Market Position and Market Share
Kerry Group plc is one of the world’s leading players in the taste and nutrition ingredients sector, headquartered in Tralee, Ireland. Following the strategic separation and full divestment of its legacy commoditized dairy processing and consumer dairy operations (Kerry Dairy Ireland), the company repositioned itself as a pure-play B2B taste, nutrition, and functional ingredients enterprise.
In the broader global taste, food flavors, and specialized nutrition ingredients market (estimated at $30B to $35B in traditional flavor/fragrance categories and over $75B in the wider specialty food ingredients sector):
- Global Ranking:Kerry Group consistently ranks among the global top 5 suppliers in the taste, food flavors, and nutrition systems industry, competing closely with Givaudan, dsm-firmenich, International Flavors & Fragrances (IFF), and Symrise.
- Market Share: In the core global food flavors and specialized savory/sweet systems domain, Kerry holds an estimated market share of approximately 8% to 10% (pure-play food flavors share is estimated around 7% to 9%, while holding higher shares exceeding 15% to 20% in customized food systems, culinary savory bases, and foodservice beverage flavor syrups).
- Operational Scale:Kerry Group generates annual revenues in the range of €6.8B to €7.0B, supplying over 10,000 products to customers across more than 140 countries.It holds a leadership position in foodservice systems, clean-label preservation, and taste-modulation solutions.
Upstream and Downstream Supply Chain Analysis
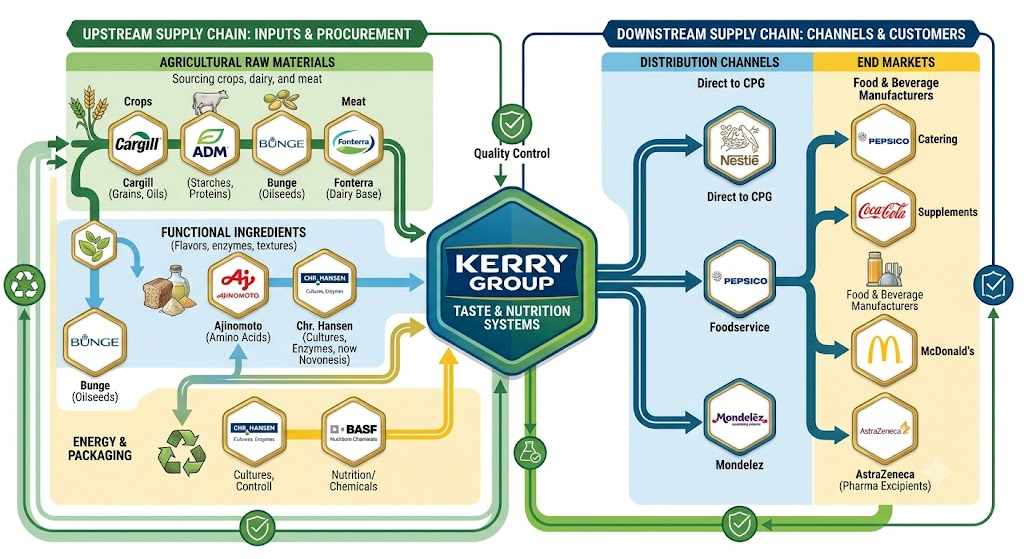
Kerry operates an integrated B2B formulation model, serving as an intermediate technological bridge between primary agricultural producers and downstream food/pharma brand owners.
Upstream Supply Chain:
- Feedstocks & Raw Materials: Kerry procures complex agricultural and botanical raw materials across three primary buckets:
- Botanicals & Natural Extracts: Vanilla beans, coffee, tea, citrus oils, spices, herbs, and botanical bioactives.
- Grains, Proteins & Fermentation Substrates: Plant protein sources (pea, soy, wheat), yeast extracts, starches, and sugars used as fermentation media for clean-label enzymes and bioculture synthesis.
- Lipids & Functional Texturants: Vegetable oils, hydrocolloids (gum acacia, pectins), and dairy derivatives (specialty whey fractions and pharmaceutical lactose).
- Key Suppliers & Sourcing Dynamics:
- Sourcing involves agricultural cooperatives, certified smallholder farmer networks (especially for vanilla in Madagascar and botanicals in India), and tier-1 commodity agribusinesses (such as Archer-Daniels-Midland, Bunge, and Cargill) for base starches, edible oils, and lecithin.
- Chemical and enzyme base precursors are supplemented by specialized fine-chemical suppliers, while botanical active components are obtained through specialized suppliers (such as Kerry’s integrated platforms like Natreon).
- Raw material pricing exposure is mitigated via index-linked pass-through pricing agreements with downstream clients.
Downstream Supply Chain:
- Channels & Customer Integration:
- Packaged Food & Beverage CPGs: Global FMCG conglomerates (e.g., Nestlé, Unilever, PepsiCo, Mondelez, Danone, Coca-Cola) rely on Kerry to co-create taste profiles, reformulate recipes for lower sodium/sugar, and improve product shelf life.
- Foodservice Chains & Quick-Service Restaurants (QSRs): Kerry provides customized beverage syrups, sauces, culinary seasoning blends, and batter/coating systems directly to major coffee shop chains, fast-food franchises, and convenience retail operators.
- Pharmaceutical & Dietary Supplement Manufacturers: Downstream contract development and manufacturing organizations (CDMOs) and OTC pharmaceutical firms utilize Kerry’s excipients, direct-tableting lactose, and masking agents for active pharmaceutical ingredients (APIs).
- Distribution Footprint: Kerry combines direct-to-customer global logistics teams for tier-1 strategic clients with specialized regional distributors (such as Univar Solutions) to service fragmented mid-tier and small-scale food manufacturers.
Competitor Analysis
Kerry Group competes primarily against specialized European and American flavor, fragrance, and specialty ingredient giants: Givaudan, dsm-firmenich, Symrise, and IFF.
Technological Comparison:
- Kerry vs. Pure-Play F&F (Givaudan, Symrise, IFF):
- Sensory Formulation & Food Systems: Givaudan and Symrise maintain an edge in proprietary aroma chemical synthesis, molecular fragrance design, and high-end fine fragrance perfumery. Kerry does not compete in personal fragrance/perfumes; instead, its engineering strength lies in full food-system integration. Kerry excels in holistic product reconstitution, combining taste, texture, clean-label preservation, and culinary functional bases (such as coatings, glazes, and sauce delivery matrices) rather than providing isolated flavor compounds.
- Reformulation & Biotechnology: Kerry has built competitive proprietary platforms: Tastesense (natural taste modulation for salt and sugar reduction without off-taste lingering) and biotechnology-derived fermentation solutions (enzymes and postbiotics). While dsm-firmenich holds deep technical capabilities in precision fermentation and complex micronutrient premixes, Kerry’s application agility allows faster turnaround times for restaurant menu innovation and CPG reformulations.
Financial Comparison:
- Revenue Scale:
- Kerry Group: ~€6.8B to €7.0B ($7.3B to $7.6B, pure taste and nutrition post-dairy divestment).
- Givaudan: ~CHF 7.4B ($8.2B to $8.5B).
- dsm-firmenich: ~€12B+ ($13B+, across nutrition, health, and beauty combined).
- IFF: ~$10.5B to $11.0B (spanning taste, scent, health, and biosciences).
- Operating Margins (EBITDA):
- Givaudan and Symrise typically achieve EBITDA margins of 20% to 22%, supported by high-margin fine fragrance and aroma chemical portfolios.
- Kerry Group generated an EBITDA margin of ~17.1% to 17.9% (targeting 18% to 20% post-dairy restructuring). Kerry’s margins were historically weighed down by bulk dairy processing; shedding lower-margin units has narrowed the gap with pure-play flavor peers.
- Balance Sheet & Returns:
- Kerry operates with disciplined leverage (net debt-to-EBITDA ratio around 2.0x), enabling sustained shareholder return programs (annual share buybacks exceeding €300M and steady dividend growth). In contrast, IFF has carried heavier debt loads resulting from large-scale mergers and acquisitions, leading to non-core divestment pressures. Kerry demonstrates high cash conversion rates (averaging 75% to 100%+ free cash flow conversion), providing strong balance sheet resilience.
Sources
- https://www.kerry.com/investors
- https://www.londonstockexchange.com/news-article/KYGA/kerry-group-interim-management-report-2024/16594241
- https://www.foodingredientsfirst.com/news/kerry-taste-innovation-fy2025-margin.html
- https://kalkine.co.uk/news/general-news/kerry-groups-taste-and-nutrition-engine-can-innovation-keep-growth-and-margins-moving-higher
- https://www.imarcgroup.com/food-flavors-market
- https://www.fortunebusinessinsights.com/flavors-and-fragrances-market-102329
- https://www.univarsolutions.com/suppliers/kerry
Back to Kerry