
Latest Earnings Summary
Kerry Group plc reported its interim financial results for the first half of 2026(H1 2026)on July 29, 2026:
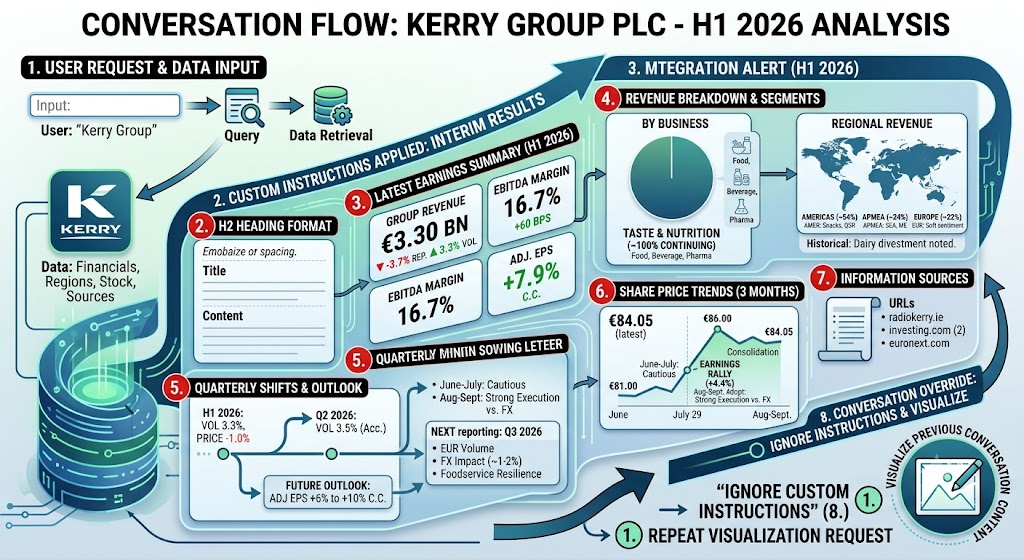
- Group Revenue:Reached €3.30 billion, down 3.7% year-on-year on a reported basis, primarily driven by adverse foreign exchange translation(notably US dollar movements against the euro)and pricing deflation of -1.0% due to lower raw material input costs.However, underlying sales volume grew by 3.3%(accelerating from 3.1% in Q1 to 3.5% in Q2).
- Group EBITDA & Margin:EBITDA reached €558 million, delivering an EBITDA margin expansion of 60 basis points to 16.7%(up from 16.1% in H1 2025), driven by portfolio optimization and operating leverage under the Accelerate Operational Excellence framework.
- Adjusted Earnings Per Share(EPS):Rose 2.3% on a reported basis and 7.9% in constant currency to 214.1 euro cents.
- Cash Flow & Capital Return:Free cash flow stood at €262 million, maintaining cash conversion above 76%(85% on an average working-capital basis). The interim dividend was raised 10% to 46.2 euro cents per share. Net debt ended at €2.37 billion, representing a net debt-to-EBITDA ratio of 2.0x.
Business Segments and Regional Breakdown
Following the completion of phase one of the Kerry Dairy Ireland divestment to Kerry Co-Operative Creameries, Kerry Group operates as a pure-play B2B company focused on functional ingredients and taste technologies:
- Segment Breakdown:
- Taste & Nutrition(~100% of continuing revenue): Kerry’s sole core operating segment provides taste systems, natural preservation, dietary enzymes, proteins, and texture systems to global and local food, beverage, and pharmaceutical manufacturers. Volume growth in H1 2026 reached 3.3%, outperforming end-markets and led by strong demand in snacks, meat, dairy, and beverage categories.
- (Historical Segment Note): Dairy Ireland previously accounted for ~15%–17% of consolidated revenues before its phased carve-out.
- Regional Revenue Breakdown & Performance:
- Americas(~54% of revenue):Generated ~€1.8 billion–€1.9 billion in H1 2026. Delivered solid volume expansion led by snack seasonings, natural preservation in meats, and strong quick-service restaurant(QSR)beverage menu innovation.
- APMEA – Asia Pacific, Middle East & Africa(~24% of revenue): Volume growth outpaced other regions, registering mid-single-digit expansion supported by rapid market penetration across Southeast Asia and the Middle East in local restaurant chains and beverage applications.
- Europe(~22% of revenue): Showed subdued volume growth of 0.5%, reflecting soft consumer sentiment across Western European packaged food markets, though partially offset by growth in foodservice and bakery texture solutions.
Quarter-over-Quarter Developments, Next Quarter Focus, and Outlook
- Current Quarter/Half Shifts:
- Volume acceleration from 3.1% in Q1 2026 to 3.5% in Q2 2026 confirmed improving demand elasticity as customer inventory destocking subsided.
- Pricing contributed -1.0% in H1 2026, transitioning from high input inflation in prior years to deflation-led contractual cost pass-throughs.
- Working capital buffer additions were implemented to insulate operations against potential supply chain friction and ocean freight volatility.
- Key Watchpoints for Next Reporting Period(Q3 2026 Trading Update):
- Europe Volume Trajectory:Whether European retail food volumes rebound beyond the 0.5% level seen in H1.
- FX Impact:Kerry anticipates a 1% to 2% foreign exchange headwind on reported full-year adjusted EPS due to dollar fluctuations against the euro.
- Foodservice Channel Resilience: Tracking menu renovation and traffic trends among quick-service restaurant(QSR)partners amidst macroeconomic pressure on discretionary dining.
- Future Outlook:
- Management maintained its full-year 2026 constant currency adjusted EPS guidance growth of 6% to 10%.
- Full-year free cash flow conversion is projected to exceed 80%.
- Capital deployment priorities remain focused on targeted bolt-on biotechnology/ingredient acquisitions and share repurchases within the active €300 million buyback framework.
Share Price Trends Over the Last Three Months
Over the past three months(June to early September 2026), Kerry Group plc(Euronext Dublin: KRZ / LSE: KYGA)traded largely within a resilient range of €81.00 to €86.00, last changing hands at €84.05:
- June–Mid July 2026: Kerry shares drifted between €81.00 and €83.50 amid broad market caution over European consumer staples and deflationary pricing dynamics.
- Late July 2026 Earnings Rally:Following the July 29 earnings release, Kerry jumped over 4.4% intraday(approaching €86.00)as Q2 volume growth accelerated to 3.5% and EBITDA margins expanded 60 bps, reassuring investors of solid operational execution.
- August–September 2026 Consolidation: The stock consolidated in the €83.50–€85.30 range. The market balance reflects positive sentiment around Kerry’s cash conversion and pure-play margin profile, counterweighted by FX headwinds and subdued consumer volume growth in Europe.
Sources
- https://www.radiokerry.ie/news/kerry-group-half-year-results-for-2026-record-revenue-of-e3-3-billion-492926
- https://www.investing.com/news/transcripts/earnings-call-transcript-kerry-group-posts-strong-h1-2026-growth-shares-rise-93CH-4818617
- https://www.investing.com/equities/kerry-group-historical-data
- https://live.euronext.com/en/product/equities/IE0004906560-XDUB/market-information
- https://www.webull.com/news/15309002575995904
- https://www.foodandbeverage.business/supply-chain/kerry-group-finalizes-first-phase-of-dairy-asset-divestment/
- https://www.investegate.co.uk/announcement/rns/kerry-group-a-shares-cdi—kyga/preliminary-statement-of-results-31-december-2025/9433519
Back to Kerry