
Market Position and Market Share
Jerónimo Martins SGPS, S.A. is an international food retail and distribution group based in Portugal, operating primarily across Poland, Portugal, and Colombia.
- Poland (Biedronka and Hebe):Jerónimo Martins holds an undisputed #1 ranking in Poland’s food retail sector through its discount banner Biedronka. Biedronka commands approximately 28% to 30% of Poland’s overall grocery retail market and over 65% of the discount segment. Poland constitutes the core of group earnings, contributing roughly 70% of consolidated sales and 80% of EBITDA. The group’s health and beauty chain, Hebe, ranks among the top drugstore banners in Poland. In 2025, the group initiated operations in Slovakia under the Biedronka brand.
- Portugal (Pingo Doce and Recheio): In its domestic market, Jerónimo Martins holds the #2 position in food retail via its supermarket banner Pingo Doce, trailing closely behind Sonae’s Continente with an estimated grocery market share of 23% to 25%. Through Recheio, Jerónimo Martins is the #1 cash-and-carry operator in Portugal, dominating wholesale food service and traditional trade distribution.
- Colombia (Ara): In Colombia, Jerónimo Martins operates Tiendas Ara, holding the #2 position in the Colombian discount grocery sector behind D1, capturing approximately 18% to 22% of the national discount grocery segment.
- Consolidated Scale:Jerónimo Martins posted consolidated group revenues of €35.99 billion and an EBITDA of €2.48 billion, reinforcing its status among the top 15 food retailers in Europe.
Upstream and Downstream Supply Chain Analysis and Key Suppliers
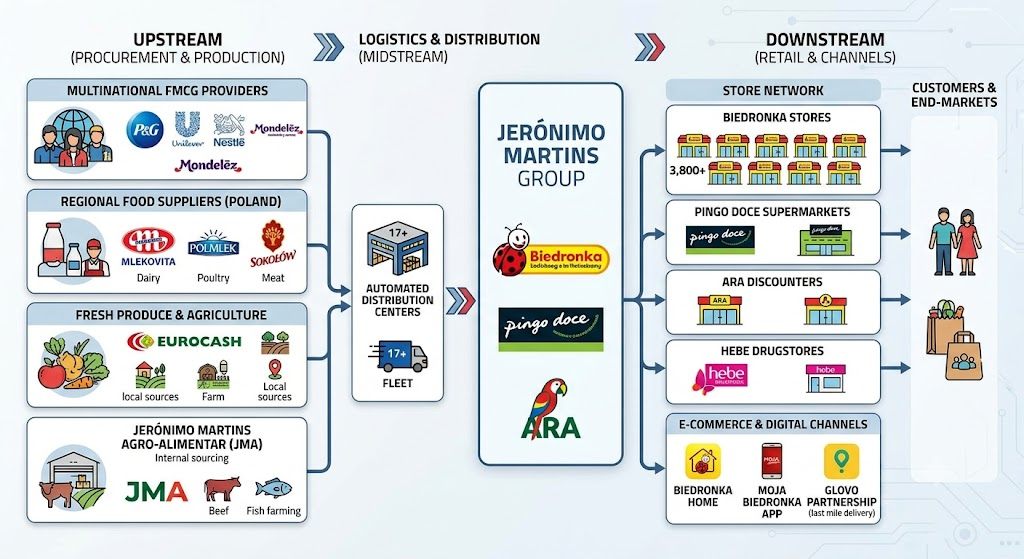
Jerónimo Martins operates an integrated, high-velocity discount and modern retail supply chain optimized for low unit costs and rapid stock turnover.
- Upstream Supply Chain (Procurement & Agribusiness):
- Direct Sourcing & Local Integration: The group follows a localization model; over 90% of food products sold in Poland and Portugal are sourced directly from domestic producers. In Poland alone, Biedronka works with over 1,800 active suppliers.
- Upstream Integration via Jerónimo Martins Agro-Alimentar (JMA): To hedge against commodity price volatility and secure sustainable protein and dairy flows, the group owns and operates upstream agribusiness operations producing Angus beef, dairy farming, and aquaculture (sea bass and sea bream) in Portugal.
- Key Suppliers: Upstream FMCG partners include multinational giants (Nestlé, Unilever, Procter & Gamble, Mondelēz, and PepsiCo), alongside regional dairy, poultry, and produce conglomerates (such as Mlekovita and Polmlek in Poland, and Lactogal in Portugal).
- Midstream Logistics and Distribution Infrastructure:
- The group owns and operates an extensive proprietary logistics network, running more than 17 major distribution centers in Poland, specialized temperature-controlled facilities in Portugal, and regional logistics hubs in Colombia.
- Cross-docking facilities and computerized inventory optimization allow daily store deliveries, maintaining ultra-low inventory carrying costs and minimizing store-level backroom storage.
- Downstream Supply Chain (Retail Network & Fulfillment):
- Physical Footprint: Downstream distribution is driven by extensive geographic density, with over 3,800 Biedronka stores in Poland, nearly 500 Pingo Doce and Recheio locations in Portugal, and more than 1,300 Ara stores in Colombia.
- Omnichannel Channels: Downstream fulfillment combines brick-and-mortar proximity stores with digital fulfillment, utilizing partnerships with on-demand delivery platforms (such as Glovo) and proprietary apps (Moja Biedronka, Biedronka Home e-commerce).
Competitor Analysis: Technical and Financial Dimensions
Jerónimo Martins’ primary competitive battles take place against hard discounters and regional supermarket chains, most notably Lidl (Schwarz Gruppe) and Dino Polska in Poland, Sonae (Continente) in Portugal, and D1 (Koba Colombia) in Colombia.
- Financial Comparison:
- Revenue Scale & Growth: Jerónimo Martins operates at a significantly larger scale (€36.0B annual revenue) compared to regional players like Dino Polska (~€6.5B to €7.0B) or Sonae’s retail arm MC (~€7.0B). However, Dino Polska exhibits faster top-line CAGR by expanding store count purely in rural and suburban Poland without taking on cross-border risk.
- Margin Profiles: Jerónimo Martins delivers a consolidated EBITDA margin of ~6.8% to 7.0%, whereas pure discounter Dino Polska achieves a higher EBITDA margin of ~8.2% to 8.8% due to full property ownership (freehold model) and centralized meat processing (Agro-Rydłyna). Conversely, Jerónimo Martins operates with superior returns on invested capital (ROIC > 18%) due to high asset turnover, high-volume leasehold store formats, and negative working capital requirements.
- Price War Defensibility: In Poland, intense price competition with Lidl has compressed retail gross margins across the sector. Jerónimo Martins has absorbed margin compression through group purchasing scale and high private-label penetration, maintaining net profit margins around 1.8% to 2.0%.
- Technical and Operational Comparison:
- Store Format & Real Estate Strategy: Dino Polska utilizes a standard, self-owned store footprint with attached parking, targeting non-urban and rural areas. Jerónimo Martins (Biedronka) deploys a flexible format strategy, converting urban real estate, residential basements, and stand-alone suburban units, maximizing customer catchment area and footfall density.
- Digitalization & CRM Architecture: Jerónimo Martins leads regional peers in customer data collection. The Moja Biedronka app boasts more than 10 million active users, rivaling Lidl’s Lidl Plus platform. The proprietary CRM provides dynamic algorithmic discounting, automated shelf replenishment forecasting, and real-time inventory tracking.
- Supply Chain Automation: While Lidl leverages centralized European logistics and Dino Polska maintains in-house logistics hubs for standardized rural stores, Jerónimo Martins invests heavily in automated picking and AI-driven route optimization across fragmented distribution networks in Poland and Colombia.
Information Sources
- https://reports.jeronimomartins.com/annual-report/2025/services/dashboard.html
- https://reports.jeronimomartins.com/annual-report/2024/_assets/downloads/mgr-management-report-jeronimomartins-ar24.pdf
- https://odpowiedzialna.biedronka.pl/pdf/report_biedronka_2024_chapter_2.pdf
- https://wbj.pl/biedronka-expands-despite-tough-market/post/147787
- https://allfoods.market/en/blog/post/top-10-largest-grocery-retail-chains-in-poland
- https://greenseedgroup.com/food-retailing-insights-in-poland-2024/
Back to Jeronimo Martins