
Latest Quarterly Earnings Summary
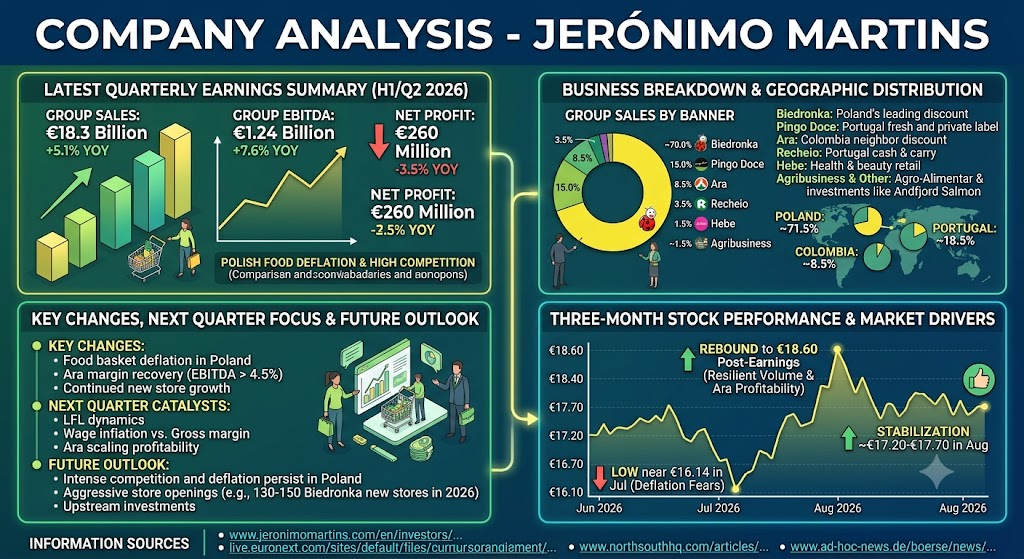
Jerónimo Martins published its H1/Q2 2026 financial results at the end of July 2026. For the first half of 2026, consolidated group sales reached €18.3 billion, representing an increase of 5.1% year-on-year.Group EBITDA rose 7.6% to €1.24 billion, expanding the EBITDA margin by 16 basis points to 6.8%.Net profit stood at €260 million, down 3.5% year-on-year, primarily reflecting significant food basket deflation in Poland, intense retail price competition, and higher operational wage and financing costs. In Q2 2026, top-line performance maintained positive volume momentum, supported by aggressive promotional pricing across all operating banners.
Business Breakdown and Geographic Distribution
According to Jerónimo Martins’ reporting structure, food distribution accounts for over 98% of total revenue, organized into key banners and regional operations:
- Biedronka (~70.0% of consolidated sales): The flagship Polish discount supermarket chain and the primary revenue driver, focused on essential groceries, everyday low pricing, and extensive private-label assortments.
- Pingo Doce (~15.0% of consolidated sales): Portugal’s leading supermarket chain, specializing in fresh produce, meal solutions, and private-label food distribution.
- Recheio (~3.5% of consolidated sales): Portugal’s largest cash-and-carry wholesaler, serving HoReCa (hotels, restaurants, cafes) and traditional retail operators.
- Ara (~8.5% of consolidated sales): The neighborhood discount store chain in Colombia, targeting high-frequency staple food purchases.
- Hebe (~1.5% of consolidated sales): A specialized health and beauty retail chain operating primarily in Poland with cross-border e-commerce operations.
- Agribusiness & Other (~1.5% of consolidated sales):Jerónimo Martins Agro-Alimentar (dairy, beef, aquaculture such as its strategic ~30% stake in Norway’s Andfjord Salmon) and corporate support operations.
Geographic Revenue Allocation and Development Status:
- Poland (~71.5% of sales): Poland remains the core earnings engine. Biedronka operates over 3,600 stores and continues to gain volume share despite facing a highly deflationary food basket environment and intense competition from domestic discount peers.
- Portugal (~18.5% of sales): A mature, highly cash-generative market. Pingo Doce and Recheio maintain clear market leadership, delivering steady low-to-mid single-digit like-for-like (LFL) sales growth driven by basket optimization and targeted promotions.
- Colombia (~8.5% of sales): The primary geographic growth frontier. Ara expanded beyond 1,700 locations with sales rising over 20% in local terms, benefiting from growing store density, brand equity, and expanding EBITDA margins as operating leverage scales up.
- Other / International (~1.5% of sales): Includes specialized cross-border retail ventures and agribusiness investments across Europe.
Key Changes, Next Quarter Catalysts, and Outlook
- Key Changes This Quarter:
- Food Basket Deflation: Polish grocery retail experienced stubborn basket deflation, forcing Biedronka to rely on volume expansion and heavy promotional campaigns to protect market share.
- Cost Management & Operating Leverage:Group EBITDA margin improved 16 bps to 6.8%, driven by logistics efficiency and margin recovery at Ara, which reached an EBITDA margin above 4.5% (up from 3.5% in prior periods).
- Store Network Expansion: Rapid footprint growth continued, with Ara adding over 50 stores in early 2026 and opening a new distribution center to bolster operational scale.
- Next Quarter Focus Points:
- Like-for-Like (LFL) Growth Dynamics: Monitoring whether Polish food inflation inflects back into positive territory or continues to suppress top-line ticket sizes.
- Wage Inflation vs. Gross Margin: Gauging the pressure of statutory minimum wage hikes in Poland and Portugal against procurement cost renegotiations.
- Colombia Profitability: Tracking whether Ara maintains its positive EBITDA trajectory amidst local consumer purchasing power headwinds.
- Future Outlook:
- Management maintained a conservative stance for H2 2026, anticipating that deflationary pressure and competitive intensity in Poland will persist without quick relief.
- Biedronka is targeting 130 to 150 net new store openings for the full year, alongside 300+ store refurbishments. Capex remains focused on logistics infrastructure, digital supply chain automation, and upstream agribusiness security.
Three-Month Stock Performance and Market Drivers
Over the trailing three-month period (June through August 2026), Jerónimo Martins (Euronext Lisbon: JMT) traded in a band between €16.10 and €18.60 per share, ending August near €17.50 to €18.20:
- June to Mid-July 2026 Consolidation: Shares dipped from around €17.70 to reach a low near €16.14 in early July, weighed down by market apprehension regarding aggressive price wars in Poland between Biedronka and Lidl, alongside persistent wage pressure.
- Late July 2026 Post-Earnings Rebound: The stock rallied sharply to a high of €18.60 on July 30 following the release of H1 2026 results, as EBITDA growth (+7.6%) and resilient volume performance alleviated fears of margin erosion.
- August 2026 Range-Bound Trading: The shares stabilized between €17.20 and €17.70 throughout August. Investors balanced solid free cash flow generation and defensive grocery demand against management’s cautious guidance regarding persistent competitive headwinds in Central Europe.
Information Sources
- https://www.jeronimomartins.com/en/investors/jeronimo-martins-shares/share-price-chart/
- https://live.euronext.com/sites/default/files/company_press_releases/attachments/2026/06/17/Connect_reportandaccountsjm1quarter2026.pdf
- https://www.northsouthhq.com/articles/jeronimo-martins-h1-2026-results-biedronka-ara-andfjord-salmon-norway-august-2026.html
- https://www.ad-hoc-news.de/boerse/news/corporate-news/jeronimo-martins-stock-holds-steady-after-h1-2026-update/69958141
- https://www.ad-hoc-news.de/boerse/news/corporate-news/jeronimo-martins-stock-holds-steady-as-investors-weigh-recent-earnings/70019135
Back to Jeronimo Martins