
Market Position and Market Share
Ibiden Co., Ltd.(TYO: 4062) is the global technology and market leader in advanced IC package substrates, specifically high-end Flip-Chip Ball Grid Array(FC-BGA) substrates based on Ajinomoto Build-up Film(ABF).
- Overall ABF Substrate Market Share: In the broader ABF substrate market(by area and total value), Ibiden holds approximately 18% to 22% global market share, ranking in the top two worldwide alongside Taiwan-based Unimicron Technology Corp.(which holds roughly 22% to 24%). Together with Shinko Electric Industries, Nan Ya PCB, and AT&S, the top five manufacturers account for approximately 75% of total worldwide ABF substrate production.
- High-End AI and Server GPU Market Dominance: In the critical segment of advanced AI accelerators and high-performance computing(HPC) chips(such as Nvidia Hopper and Blackwell series architecture), Ibiden commands an estimated 60% to 70% market share. Ibiden serves as the primary development partner and lead production source for leading-edge, large-body(>80mm x 80mm to >100mm x 100mm), high-layer-count(16 to 24+ layers) substrates.
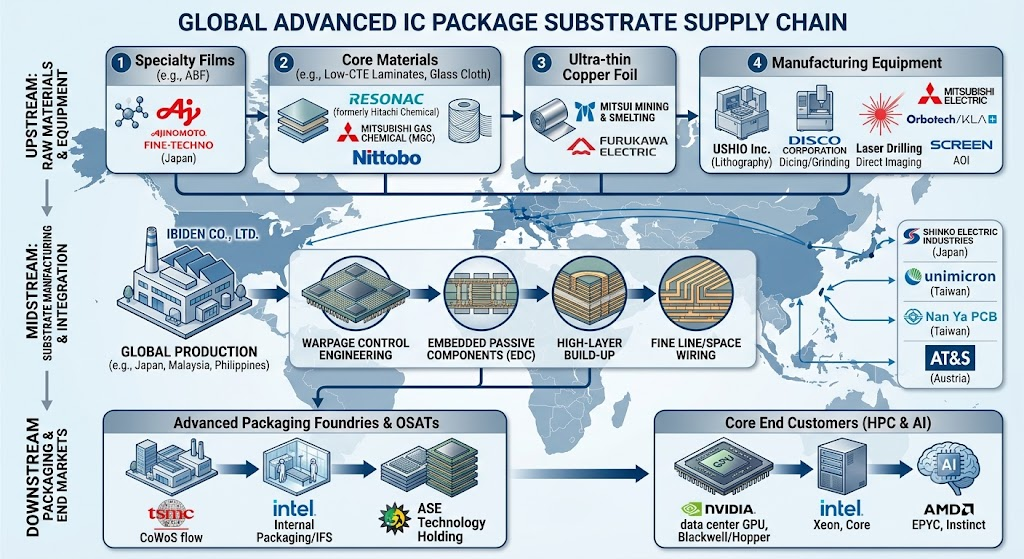
Supply Chain Analysis and Key Suppliers
Upstream: Raw Materials and Manufacturing Equipment
Advanced ABF substrate manufacturing is heavily dependent on highly consolidated specialty materials and specialized lithography tools:
- Dielectric Build-up Film: Ajinomoto Fine-Techno(Ajinomoto Group) commands an effective global monopoly(>95% share) on the supply of ABF resin film, making it the most critical single-point supplier for Ibiden’s substrate build-up layers.
- Core Materials and Glass Cloth: Low-CTE(coefficient of thermal expansion) core copper-clad laminates(CCL) and advanced low-dielectric glass cloth are sourced from Resonac(formerly Hitachi Chemical), Mitsubishi Gas Chemical(MGC), and Nitto Boseki(Nittobo). Nittobo’s low-thermal-expansion T-glass yarn is essential for warpage control in large-footprint substrates.
- Ultra-Thin Copper Foils: Procured from specialty metal refiners such as Mitsui Mining & Smelting(Mitsui Kinzoku) and Furukawa Electric, focusing on micro-profile foil to maintain fine line/space wiring integrity.
- Capital Equipment: Production lines rely on Ushio Inc. for advanced projection exposure systems/steppers, DISCO Corporation for precision dicing and surface grinding, Mitsubishi Electric and Via Mechanics for high-speed laser via drilling, and Orbotech(KLA) or SCREEN Holdings for automated optical inspection(AOI) and direct imaging.
Midstream: Manufacturing and Proprietary Packaging Integration
Ibiden processes raw materials at key domestic production facilities in Gifu Prefecture, Japan(including the Ogaki, Ono, and the high-volume Gama plant), supplemented by offshore volume assembly and substrate operations in Malaysia and the Philippines:
- Warpage Control Engineering: Mitigates the physical deformation of ultra-large multi-chip modules under extreme reflow temperatures by precisely balancing core CTE with die layer expansion.
- Embedded Passive Components: Incorporates embedded decoupling capacitors(EDC) inside the internal substrate stack, shortening power delivery paths for AI processors and preserving substrate surface area for High Bandwidth Memory(HBM) integration.
Downstream: Foundries, Packaging Houses, and Fabless/IDM Leaders
- Advanced Packaging Foundries and OSATs: Ibiden delivers processed FC-BGA substrates directly to foundries and OSATs for 2.5D/3D packaging assembly, most notably TSMC(for the CoWoS-S/L packaging flows), Intel(for internal assembly and IFS packaging), and ASE Technology Holding.
- Core End Customers:
Competitor Analysis: Technical and Financial Comparison
Peer Landscape
- Unimicron Technology Corp.(Taiwan, 3037.TW):Ibiden’s closest peer in production capacity and bleeding-edge qualifications.
- Shinko Electric Industries Co., Ltd.(Japan, 6967.T):High-precision Japanese peer with historical leadership in Intel CPU packaging and AMD MI300 multi-chiplet designs.
- Nan Ya PCB(Taiwan, 8046.TW) and Kinsus(Taiwan, 3189.TW): High-volume suppliers weighted towards mid-range server CPUs, networking silicon, and consumer devices.
- AT&S(Austria, ATS.VI): European competitor with manufacturing presence in China and Malaysia, heavily invested in advanced packaging for Intel and high-layer server architectures.
Technical Comparison
- Layer Count and Size Capability:Ibiden leads the industry in manufacturing yields for substrates exceeding 20 layers and surface areas above 80mm x 80mm.While Unimicron has expanded high-layer capabilities at its Yangmei S3 plant, Ibiden maintains superior yield stability at the extreme ends of the CoWoS-L substrate envelope.
- Wiring Density(Line/Space): Ibiden achieves line/space(L/S) dimensions below 9/9 micrometers on standard high-density build-up layers, pushing toward semi-additive processes(SAP) that interface with silicon/RDL interposers. Shinko matches Ibiden’s micro-bump fine-pitch assembly precision, but Ibiden has wider volume deployment in hyperscale AI architectures.
- Power Integrity Innovation: Ibiden’s proprietary embedded capacitor manufacturing represents a technological moat. Competitors primarily place passive components on the outer substrate surface, which limits space for surrounding HBM stacks and increases transient voltage drop.
Financial Comparison
- Profitability and ASP Structure: Ibiden historically achieves higher gross margins(typically 25% to 35% during upcycles) and operating margins(15% to 20%+) than Taiwan-based peers due to its focus on high-ASP flagship AI processors. By contrast, Unimicron and Nan Ya PCB experience wider margin fluctuations(gross margins ranging from 12% to 25%) due to greater exposure to consumer electronics, PCs, and mature networking nodes.
- Revenue and Product Mix: Unimicron generates larger total consolidated PCB and substrate revenues due to high-volume rigid-flex and conventional multilayer HDI boards. In contrast, Ibiden’s top line is more concentrated in high-value electronics(IC packaging substrates generating >50% of group revenue, complemented by its diesel particulate filter/ceramics division).
- Capital Discipline and Balance Sheet: Ibiden operates with a conservative capital structure typical of top-tier Japanese industrial firms, maintaining an equity ratio exceeding 65% alongside targeted capital expenditures subsidized by the Japanese Ministry of Economy, Trade and Industry(METI). Unimicron deploys higher aggressive Capex cycles, which exposes it to elevated depreciation headwinds during market downcycles.
Information Sources
- https://www.ibiden.com/
- https://www.tpca.org.tw/en/news_detail.php?menu_no=597&mod_no=1&news_no=27942
- https://www.yolegroup.com/press-release/advanced-ic-substrate-reach-the-stars/
- https://artificialanalysis.ai/microevals/semiconductor-analysis-1752500714706
- https://www.investing.com/equities/ibiden-co-ltd
- https://en.wikipedia.org/wiki/Ibiden
back to Ibiden