
Market Position and Market Share
Hoya Corporation occupies dominant, high-barrier-to-entry niche positions across two core segments: the Information Technology (IT) Business and the Life Care Business.
- Extreme Ultraviolet(EUV) Photomask Blanks:Hoya is the global market leader with an estimated 70% to 80% market share in the supply of EUV mask blanks utilized by leading-edge logic and memory fabs. The company operates in a near-duopoly with Shin-Etsu Chemical, serving as an indispensable critical enabler for sub-5nm, 3nm, and 2nm semiconductor manufacturing nodes.
- Glass Substrates for Hard Disk Drives(HDDs): Hoya maintains a 100% monopoly market share in nearline and data center 3.5-inch high-capacity HDDs utilizing glass substrate platters. Hoya pioneered the commercialization of glass disks, completely displacing aluminum platters in high-density, helium-sealed multi-disk enterprise drives.
- Eyeglass Lenses: Hoya ranks #2 globally behind EssilorLuxottica, commanding an estimated 15% to 18% global volume market share (and over 35% in select regions including Japan). It is particularly prominent in high-index resin materials, personalized progressive lenses, and pediatric myopia control lenses(MiYOSMART).
- Intraocular Lenses(IOLs):Hoya ranks #3 globally (trailing Alcon and Johnson & Johnson Vision), commanding approximately 10% to 12% global market share with significant market leadership in Japan (over 30% share) and strong positions in Europe via its Vivinex foldable hydrophobic acrylic IOL platform.
- Medical Endoscopes: Operating through its PENTAX Medical division, Hoya ranks #3 globally with roughly 8% to 10% market share, trailing Olympus (the dominant leader at ~70%) and Fujifilm.
Supply Chain Analysis and Key Suppliers
Upstream Supply Chain(Raw Materials and Capital Equipment)
Hoya operates primarily as a precision optical glass and advanced chemical/materials processor, relying on strict upstream inputs:
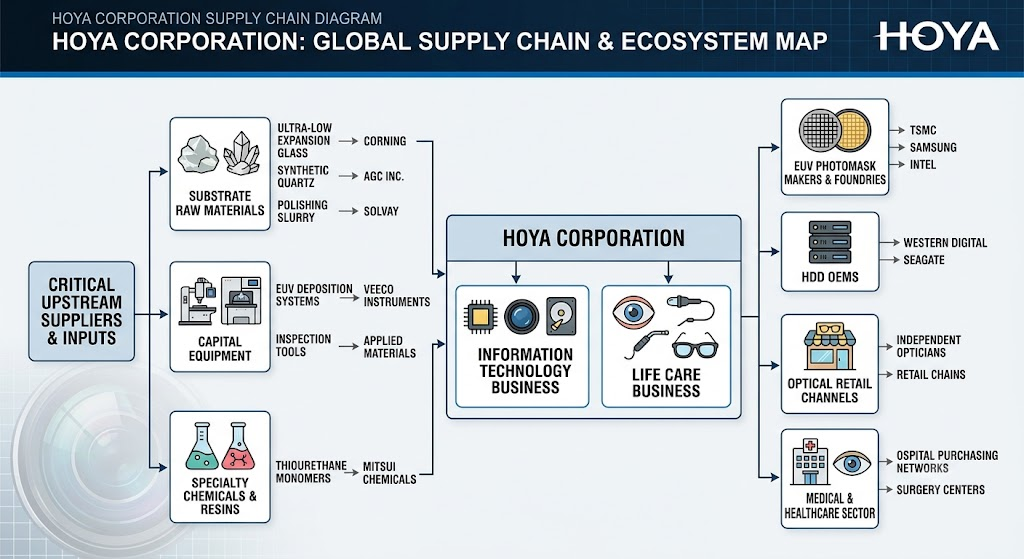
- Ultra-Low Expansion(ULE) Glass and Fused Silica Substrates: For EUV photomask blanks, thermal stability at zero thermal expansion is mandatory to avoid pattern distortion under high-energy extreme ultraviolet exposure. Key upstream suppliers include Corning Inc.(supplying titanium-doped silicate glass such as ULE glass substrates) and AGC Inc.(providing synthetic quartz and high-purity glass).
- Rare Earths and Optical Precursors: High-purity cerium oxide, lanthanum oxide, and silica powders for precision polishing slurry are sourced from specialty chemical houses such as Solvay, Showa Denko(Resonac), and Mitsui Mining & Smelting.
- Thin-Film Deposition and Ion Beam Sputtering Systems: EUV blanks require 40 to 50 alternating atomic layers of molybdenum(Mo) and silicon(Si) followed by ruthenium(Ru) capping and tantalum-based absorber layers. High-precision ion beam sputtering(IBS) deposition systems and defect inspection tools are procured from specialized capital equipment makers including Veeco Instruments and Applied Materials.
- Optical Resins and Monomers: For the Life Care eyeglass division, Hoya synthesizes both proprietary polymers and sources thiourethane monomers(MR Series) from Mitsui Chemicals, which form the foundation for thin, ultra-high-refractive-index lenses(1.60, 1.67, and 1.74 index).
Downstream Value Chain and Channel Integration
Hoya’s downstream pathways bifurcate cleanly between commercial healthcare distribution and semiconductor integration:
- Semiconductor Photomask Makers and Foundries: Hoya ships blank plates directly to captive mask shops within integrated device manufacturers and pure-play foundries—principally TSMC, Samsung Foundry, and Intel—as well as merchant photomask makers like Toppan Photomask(Photronics/Dai Nippon Printing).
- Storage Device OEMs: Finished HDD glass platters are integrated directly into high-capacity enterprise helium drives manufactured by Western Digital and Seagate Technology.
- Healthcare Channels: Eyeglass lenses pass through independent optical retail chains, wholesale buying groups, and eye clinics. Intraocular lenses and PENTAX endoscopes are distributed directly through hospital purchasing networks, medical device distributors, and ambulatory surgery centers(ASCs).
Competitor Analysis: Technical and Financial Comparison
Information Technology Segment: Hoya vs. Shin-Etsu Chemical & AGC Inc.
- EUV Photomask Blanks:
- Technical Comparison: Hoya pioneered phase-shift and low-n absorber EUV mask blanks, setting the de facto industry defect-density benchmark (less than 0.01 defects per cm² at sub-20nm resolution). Its primary competitor, Shin-Etsu Chemical, entered EUV blanks by leveraging its deep internal silicon wafer, organosilicon chemistry, and synthetic quartz supply chain. While Shin-Etsu excels in vertical material integration, Hoya maintains superior defect inspection yield and longer baseline qualifications across leading-edge foundry tools. AGC Inc.supplies glass substrates and has made strides in coated blanks, but remains behind Hoya in volume shipments for critical-layer High-NA EUV logic.
- Financial Metrics: Hoya’s IT segment delivers structural operating margins regularly exceeding 45% to 50%, supported by pricing power and long-term supply agreements. Shin-Etsu’s electronic materials division demonstrates comparable profitability (~30% to 35% overall company operating margin), but operates with broader exposure to cyclical commodity PVC and silicon wafer wafer-pricing cycles.
Life Care Segment: Hoya vs. EssilorLuxottica & Alcon
- Vision Care(Eyeglass Lenses):
- Technical & Channel Comparison:EssilorLuxottica represents a fully integrated optical giant owning premier retail chains(LensCrafters, Sunglass Hut, GrandVision) and flagship lens IP(Varilux, Crizal, Transitions). Hoya cannot match EssilorLuxottica’s retail footprint, compelling Hoya to partner with independent opticians and position itself as an unbiased partner. Technically, Hoya matches EssilorLuxottica in surface surfacing algorithms(iD FreeForm Design Technology) and holds clinical advantages in pediatric myopia control with its defocus multi-segment(D.I.M.S.) technology in MiYOSMART, competing head-to-head with Essilor’s Stellest.
- Financial Metrics: EssilorLuxottica generates over €25B in annual revenue with operating margins around 16% to 18%, constrained by the high retail overhead of physical stores. Hoya’s Vision Care division operates on an asset-lighter model, achieving segment operating profit margins of roughly 20% to 22%.
- Medical Products(IOLs):
- Technical Comparison: In the premium IOL space, Alcon(AcrySof, PanOptix, Vivity) and Johnson & Johnson Vision(Tecnis Synergy, Eyhance) control advanced trifocal, toric, and extended depth of focus(EDOF) markets. Hoya’s Vivinex series differentiates itself through pre-loaded injector reliability(multiSert/iSert) and low rates of posterior capsule opacification(PCO), though its portfolio is historically weighted toward monofocal and hydrophilic/hydrophobic baseline lenses rather than ultra-premium presbyopia-correcting optics.
Information Sources
- https://www.hoya.com/ir/2024/en/review/it.html
- https://www.hoya.com/ir/2025/en/review/lifecare.html
- https://dataintelo.com/report/global-euv-photomask-blanks-market
- https://www.futuremarketinsights.com/reports/prescription-lens-market-share-analysis
- https://www.snsinsider.com/reports/euv-mask-blanks-market-7334
- https://www.mordorintelligence.com/industry-reports/global-intra-ocular-lens-market-industry
back to Hoya