
Market Position and Market Share
Groupe ADP(Aéroports de Paris SA)is one of the largest airport operator networks globally by passenger traffic, holding a commanding position in European and global commercial aviation.
- Domestic Market Dominance:In mainland France, Groupe ADP manages the key aviation assets of the Paris region, including Paris-Charles de Gaulle(CDG), Paris-Orly(ORY), and Paris-Le Bourget(LBG). Together, CDG and ORY handled 107.0 million passengers in 2025(+4.2% YoY), capturing virtually all commercial international and long-haul air traffic in the Paris capital region.
- Global Footprint and Volume:Across its worldwide portfolio—encompassing wholly-owned operations, majority-controlled subsidiaries(such as TAV Airports with 113 million passengers), and strategic equity participations(including GMR Airports with 121.3 million passengers)—Groupe ADP’s broader network welcomed approximately 379.0 million passengers in 2025(+4.2% YoY).This total volume places Groupe ADP neck-and-neck with Spain’s Aena(384.8 million global network passengers in 2025)at the very top of worldwide airport operator passenger rankings.
- Hub Competitiveness:Paris-Charles de Gaulle welcomed nearly 72 million passengers in 2025, ranking as the largest airport in France and the 3rd busiest passenger airport in Europe(trailing only London Heathrow and Istanbul Airport).CDG serves over 311 destinations with a connecting passenger transfer rate of 29.5%, solidifying its ranking as Europe’s largest hub for intercontinental connectivity. In cargo, CDG handles over 2 million metric tonnes of freight and mail annually, operating as a primary European logistics gateway hosting global hubs for Air France-KLM Cargo, FedEx, and GeoPost/La Poste.
Supply Chain and Value Chain Analysis
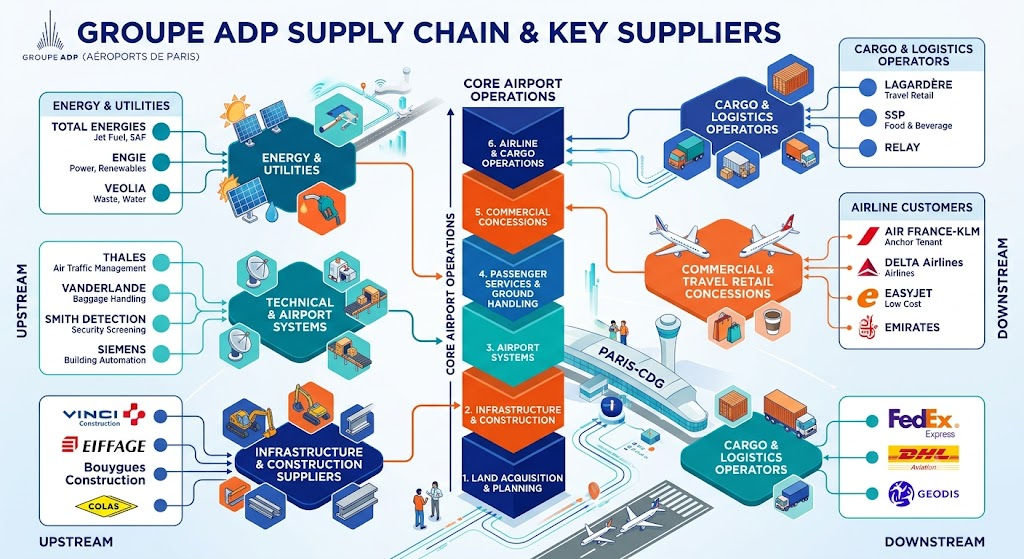
Groupe ADP serves as the orchestrator and infrastructure custodian of a complex aviation and airport city ecosystem, bridging physical infrastructure developers with operational service providers and downstream travel consumers.
- Upstream Infrastructure, Engineering, and Equipment Suppliers:
- EPC and Civil Engineering Contractors: Groupe ADP relies heavily on major European construction conglomerates for civil engineering, runway resurfacing, and terminal construction/expansion under its multi-billion-euro investment cycles. Key suppliers include Bouygues Construction, Vinci Construction, and Eiffage.
- Specialized Airport Systems & Baggage Handling: Terminal automation and high-speed baggage handling systems(BHS)are mission-critical. Key suppliers include Vanderlande(Toyota Industries)and BEUMER Group for automated sorting, alongside Siemens for facility automation and building management platforms.
- Aviation Security Screening and Border Control: Passenger and cabin luggage screening relies on advanced computed tomography(CT)and explosive detection systems supplied by Smiths Detection, Leidos, and Morpho/Idemia, combined with biometric automated border control(ABC)e-gates developed by Thales and Idemia.
- Air Traffic and Navigational Infrastructure: Surface movement control, automated radar, and airport surveillance systems are procured from specialized defense/aerospace suppliers such as Thales and Indra Sistemas, coordinating directly with the French civil aviation regulator DGAC/DSNA.
- Ground Power and Energy Transition: Suppliers like TotalEnergies and Engie supply conventional power, sustainable aviation fuel(SAF)logistics, hydrogen infrastructure development, and airfield electrical equipment(e.g., 400Hz ground power units and pre-conditioned air units).
- Midstream Operations and On-Site Service Providers:
- Ground Handling, Ramp, and De-icing: While ADP regulates space and license concessions, third-party ground handlers—such as Alyzia, Swissport, and Menzies Aviation—operate ramp services, pushback, and aircraft handling alongside Air France’s in-house ground operations.
- Airport Security and Facilities Management: Specialized security screening personnel are contracted through private service providers like ICTS Europe, Securitas, and Brink’s, operating under the oversight of the French border police(PAF)and gendarmerie(GTA).
- Downstream Commercial and Retail Value Chains:
- Duty-Free and Travel Retail: Downstream retail value extraction is executed primarily through joint ventures. Under its hospitality brand Extime, ADP operates joint ventures with global travel retail operators, most notably Extime Duty Free Paris(a 50/50 JV with Lagardère Travel Retail)and food and beverage concessions operated with Select Service Partner(SSP)and Areas.
- Air Carriers:ADP’s primary B2B corporate customers are commercial airlines, dominated by the SkyTeam alliance and anchor tenant Air France-KLM, alongside low-cost carriers(such as easyJet, Transavia, and Vueling)and intercontinental carriers(Delta, United, Emirates, Qatar Airways).
Competitor Analysis: Technical and Financial Comparison
Groupe ADP competes with other major listed and public-private European airport groups, most notably Aena SME SA(Spain)and Fraport AG(Germany).
Technical and Operational Comparison
- Dual-Airport Complementarity vs. Concentrated Hubs:
- Groupe ADP: Operates a balanced dual-hub architecture in its core Paris market. CDG handles long-haul intercontinental traffic, legacy flag carriers, and hub-and-spoke transfer connections, while Orly specializes in point-to-point European, domestic, and North African routes. This mitigates operational bottlenecks compared to single-hub models.
- Fraport AG: Concentrates its German operations heavily on Frankfurt Airport(FRA). FRA operates near maximum runway capacity constraints and strict night flight curfews, though it maintains superior intermodal rail-air connectivity via the ICE high-speed train terminal directly attached to Terminal 1.
- Aena: Operates an extensive network model with Madrid-Barajas(MAD)serving as the premier hub for European-Latin American corridors, complemented by high-margin tourist-heavy coastal and island airports(Barcelona, Málaga, Palma de Mallorca)with lower operational complexity than CDG.
- Engineering and Technical Services Export: ADP possesses an internal design, architecture, and project management arm(ADP Ingénierie), which exports technical airport engineering and master-planning worldwide. Fraport and Aena rely comparatively more on external engineering consultancies or concession management entities.
- Decarbonization and Infrastructure Innovation: CDG and Orly are pioneering large-scale integration of SAF storage pipelines and test-bed programs for eVTOL(electric vertical takeoff and landing)aircraft at Pontoise aerodrome. ADP has SBTi-validated net-zero emission trajectories for Scopes 1 and 2 operations across its Parisian hubs.
Financial Comparison
| Metric(FY2025) | Groupe ADP | Aena SME SA | Fraport AG |
| Consolidated Revenue | €6.70B(+8.9% YoY) | €6.38B(+9.5% YoY) | €4.21B(+8.2% YoY, ex-IFRIC 12) |
| EBITDA | €2.32B(+12.3% YoY) | €3.79B(+7.8% YoY) | €1.44B(+10.4% YoY) |
| EBITDA Margin | ~34.6% | ~59.3% | ~34.2% |
| Net Result(Group Share) | €382M(+11.7% YoY) | €2.14B(+10.5% YoY) | €468.1M(-6.7% YoY) |
| Total Global Network Pax | ~379.0M | ~384.8M | ~184.0M |
- Margin and Profitability Structure:Aena delivers structurally higher profitability(EBITDA margin approaching 60%)due to its leaner labor cost structure, absence of heavy winter operations/de-icing overheads, high commercial spending across seasonal tourist traffic, and network cross-subsidization in Spain. ADP generates higher gross revenue through retail, real estate, and engineering services, but its EBITDA margin(~35%)reflects heavier French regulatory charges, higher direct personnel costs, and concession amortization.
- Capital Intensity and Debt Dynamics: Both ADP and Fraport have carried heavy leverage from extensive multi-year CapEx programs(such as Fraport’s Terminal 3 construction in Frankfurt and ADP’s €8.2bn Economic Regulation Agreement cycle). Aena maintains a lower net debt-to-EBITDA leverage profile(approx. 1.37x), providing greater financial flexibility for international mergers and acquisitions.
Sources
- https://essentiel.groupe-adp.com/en/groupe-adp-performance-in-2025
- https://essentiel.groupe-adp.com/en/the-new-momentum-in-the-aviation-market-is-becoming-clearer
- https://moodiedavittreport.com/groupe-adp-passenger-traffic-climbs-4-2-in-2025/
- https://airportir.com/operator-profiles/features/groupe-adp-record-2025-results-a-landmark-indian-rebalancing-and-an-8-2bn-paris-investment-cycle
- https://www.investing.com/news/company-news/aena-2025-presentation-record-profit-drives-17-stock-surge-93CH-4524352
- https://www.aena.es/en/press/aena-earns-1579.4-million-euros-in-the-first-nine-months-of-2025.html
- https://www.fraport.com/en/newsroom/press-releases/2026/bpk/2025-fiscal-year–positive-free-cash-flow.html
- https://airlinergs.com/fraport-reports-stronger-revenue-and-positive-cash-flow-in-2025/
Back to Groupe ADP