
Latest Quarterly Financial Highlights
Galp Energia SGPS, S.A. reported its 2Q 2026 results showing substantial earnings expansion driven by elevated Brent realizations and improved operational delivery across its key divisions:
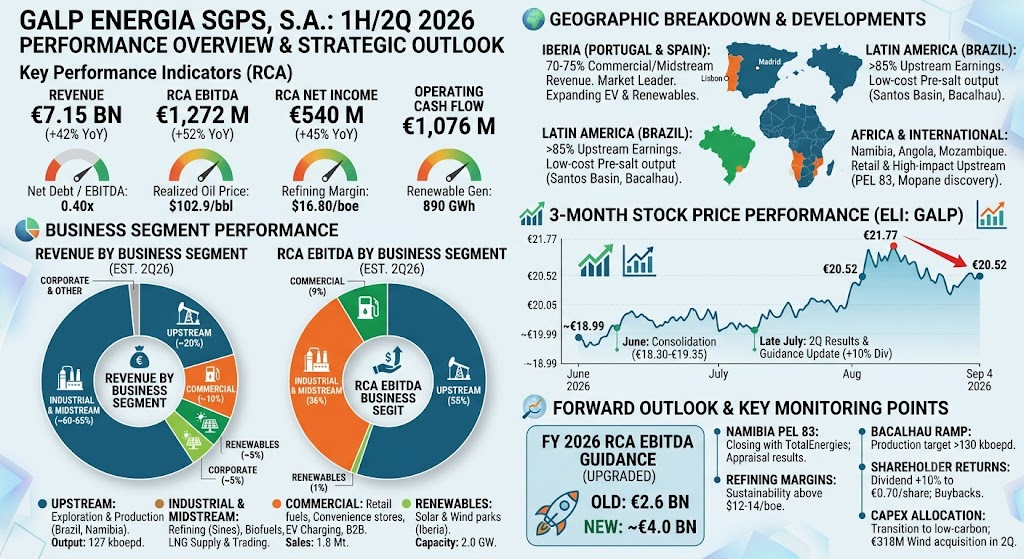
- Total revenue reached €7.15 billion, up 42% year-on-year.
- Group RCA EBITDA rose 52% year-on-year to €1,272 million (compared to €840 million in 2Q 2025).
- RCA EBIT climbed to €1,055 million (+59% YoY), while RCA Net Income reached €540 million (+45% YoY). Under IFRS accounting, net income reached €762 million.
- Operating Cash Flow (OCF) amounted to €1,076 million, and Cash Flow from Operations (CFFO) totaled €1,121 million.
- Capital expenditures (Capex) stood at €496 million, which included a €318 million cash outflow for the acquisition of an operational onshore wind portfolio in Spain.
- Net debt stood at €1.38 billion, bringing the Net Debt to RCA EBITDA ratio down to a conservative 0.40x (versus 0.51x in 2Q 2025).
Revenue & Segment Breakdown
Galp classifies its corporate activities into four primary reporting business segments, complemented by Corporate & Others:
- Upstream: Focuses on exploration, development, and crude oil/natural gas extraction, primarily anchored in the deepwater offshore pre-salt basins in Brazil (such as the Santos Basin, Tupi, and Bacalhau) alongside key exploration rights in Namibia (Mopane discovery, PEL 83). In 2Q 2026, Upstream generated €700 million in RCA EBITDA (representing ~55% of total divisional EBITDA), benefiting from production of 127 kboepd and a realized oil price indicator of $102.9/bbl.
- Industrial & Midstream:Covers refining system operations (chiefly the Sines refinery complex), biofuels processing, logistics, and wholesale natural gas/LNG supply and global trading operations.The segment accounts for the largest proportion of gross revenue (~60% to 65% of top-line group sales) and delivered €458 million in RCA EBITDA (~36% of divisional EBITDA), driven by a realized refining margin of $16.80/boe and increased throughput.
- Commercial:Encompasses retail distribution of oil products, service stations across the Iberian Peninsula, non-fuel retail convenience stores, B2B commercial fuel sales, and decentralized energy solutions (EV charging, power, and distributed solar installations).The division generated €113 million in RCA EBITDA (~9% of divisional EBITDA) on 1.8 million tons of oil product sales and 2.4 TWh in electricity sales.
- Renewables:Consists of utility-scale solar photovoltaic parks and onshore wind power generation assets across Iberia.In 2Q 2026, Renewables generated €11 million in RCA EBITDA (~1% of divisional EBITDA), supported by the full consolidation of a newly acquired 351 MW wind portfolio in Spain and total renewable generation sales of 890 GWh.
Geographic Breakdown & Developments:
- Iberia (Portugal & Spain): Generates approximately 70% to 75% of group commercial and midstream revenues. Domestic market operations in Portugal maintain dominant market share in refining and fuel retailing, while expansion in Spain focuses on retail network modernization, EV charging infrastructure, and wind/solar generation scaling.
- Latin America (Brazil): Represents over 85% of Upstream earnings. Operations in the pre-salt Santos Basin deliver steady low-cost crude output, reinforced by the production ramp-up of the Bacalhau FPSO.
- Africa & International:Covers oil and convenience retailing in Southern Africa (such as Mozambique, Angola, and Cape Verde) and high-impact upstream appraisal campaigns, notably offshore Namibia, where farm-out transactions to strategic partners like TotalEnergies have established long-term development optionality.
Key Operational Changes, Forward Outlook & Metrics
Quarterly Changes:
- Upstream production reached 127 kboepd, representing a 12% YoY increase.While planned platform maintenance caused a minor sequential slowdown from 1Q 2026 (129 kboepd), high well productivity and initial ramp-up phases from the Bacalhau project substantially offset the outages.
- Industrial availability at the Sines refinery rebounded to near-full capacity, handling 22.6 mboe of processed crude, allowing the company to capture wide distillate cracks and achieve a realized margin of $16.80/boe.
- Wind asset acquisition integration added 351 MW of operating capacity, taking Galp’s operational renewable footprint to 2.0 GW.
Next Quarter Observations & Future Guidance:
- Full-Year 2026 Upgraded Guidance:Galp raised its full-year 2026 RCA EBITDA guidance to approximately €4.0 billion (up from initial baseline assumptions of €2.6 billion) and guided full-year Operating Cash Flow (OCF) toward €3.0 billion, backed by an updated macro assumption of $80/bbl Brent and $13/boe refining margins.
- Shareholder Returns:Supported by low leverage (0.40x net debt/EBITDA), the Board proposed a 10% increase in the 2026 dividend per share to €0.70 (with an interim €0.35/share distributed in August 2026), alongside ongoing share buyback execution.
- Monitoring Points for Q3/Q4:
- Namibia Block PEL 83 (Mopane discovery): Regulatory closing and operator transition to TotalEnergies, alongside appraisal drilling updates and flow-test valuations.
- Refining Margin Normalization: Whether European refining cracks sustain above $12-$14/boe amid fluctuating global product inventory levels.
- Bacalhau Production Ramp: Connectivity milestones of additional producer wells to solidify base upstream volumes above 130 kboepd.
3-Month Stock Price Performance & Driver Analysis
Over the past three months (early June 2026 to early September 2026), Galp Energia shares traded on Euronext Lisbon (ELI: GALP) showed resilience, rising from approximately €18.99 in early June to €20.52 by September 4, 2026, representing an overall gain of ~8.06%:
- June 2026 (Consolidation): The stock consolidated between €18.30 and €19.35 due to broader macroeconomic concerns surrounding global oil demand moderation and European energy price softness.
- Late July 2026 (Earnings Volatility and Guidance Spike): Upon the release of 2Q 2026 figures in late July, the stock initially dropped below €19.00 due to consensus misses on immediate accounting revenue and reported EPS. However, the market quickly repriced the stock upward toward the €20.00-€20.50 level after digesting management’s raised full-year EBITDA target to €4.0 billion, higher cash flow conversion, and a 10% dividend hike.
- August – Early September 2026 (Breakout toward €21.50+ and Stabilization):In mid-to-late August, the stock touched multi-week highs of €21.77 following the completion of strategic M&A milestones (TotalEnergies closing on Namibia PEL 83 operator acquisition) and robust interim dividend delivery (€0.35 ex-date in mid-August), before consolidating back to €20.52 amid broader market profit-taking.
Sources
- https://www.galp.com/corp/en/investors/publications-and-announcements/investor-announcements/investor-announcement/id/1550/galp-2q24-results
- https://www.galp.com/corp/Portals/0/Recursos/Inv%202Q26/2Q26%20Report.pdf
- https://www.investing.com/news/transcripts/earnings-call-transcript-galp-lifts-2026-outlook-after-h1-profit-strength-q2-miss-93CH-4813039
- https://www.investing.com/equities/galp-energia
- https://simplywall.st/stock/enxtls/galp
Back to Galp Energia