
Market Position and Market Share
Fast Retailing ranks as the world’s 3rd largest specialized apparel retailer by revenue, trailing only Inditex(Zara) and H&M Group. By market capitalization among pure-play specialty apparel retailers, Fast Retailing consistently contends for the #2 global spot behind Inditex. In its home market of Japan, Fast Retailing is the undisputed market leader, capturing roughly 12% to 15% of the domestic apparel retail sector. Globally, within the broader and highly fragmented $1.8 trillion apparel industry, Fast Retailing commands an estimated 1.2% to 1.4% market share, with revenue for FY2024 reaching 3.10 trillion yen(~$20.8 billion USD) and climbing toward 3.97 trillion yen in FY2026 guidance.
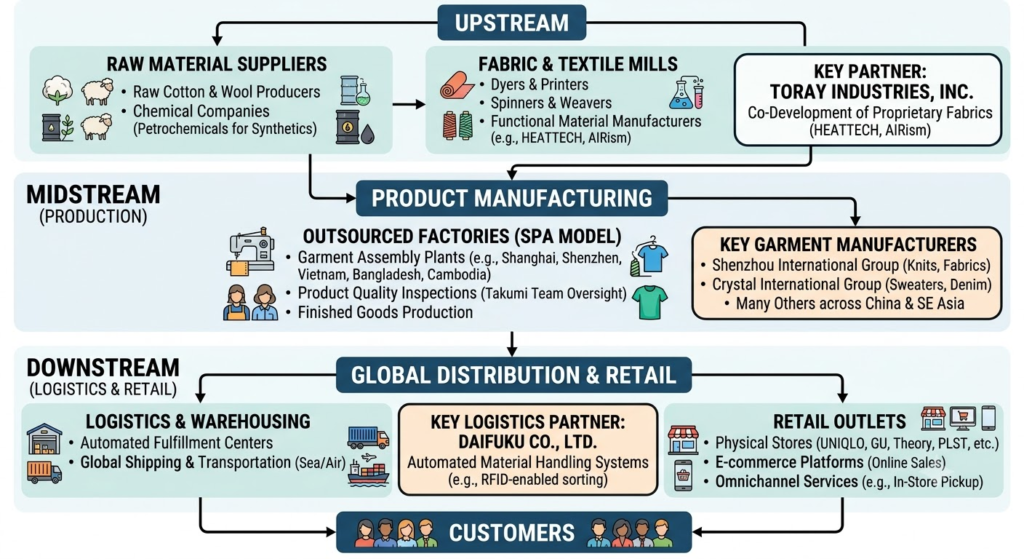
Supply Chain Upstream and Downstream Analysis
Upstream(Raw Materials & Advanced Textile R&D):
Unlike peers relying on off-the-shelf fabrics, Fast Retailing establishes deep strategic partnerships with upstream synthetic chemical and textile conglomerates. Its most critical supplier is Japan’s Toray Industries, with whom it co-develops proprietary, tech-enabled functional fibers such as Heattech, AIRism, and Ultra Light Down. It also sources high-grade natural staples such as extra-fine Merino wool and premium cotton in bulk. By locking in large-scale, long-term procurement agreements, Fast Retailing secures material exclusivity, stabilizes input costs, and raises barriers to entry.
Midstream(Production & Tier-1 Manufacturing):
Fast Retailing does not own manufacturing plants; it operates an outsourced SPA(Specialty store retailer of Private label Apparel) model. Rather than fragmenting production across thousands of suppliers, it concentrates ~80% of its volume across approximately 400 to 500 strategic partner factories primarily located in China, Vietnam, Bangladesh, Cambodia, and Indonesia. Key manufacturing groups include Shenzhou International(knitted garments and performance fabrics) and Crystal International. Fast Retailing deploys its own proprietary “Takumi Team”(master textile artisans, dyes, and production engineers) directly into partner facilities to oversee quality control, machine calibration, and worker productivity.
Downstream(Logistics, Omnichannel & Retail Network):
The downstream operation centers on fully automated fulfillment hubs, developed in technical partnership with Daifuku, which feature automated picking cranes and RFID automated sorting. Over 3,500 physical stores worldwide(led by Uniqlo and GU) utilize RFID checkout systems, capturing real-time sales velocity and inventory levels. This demand signal feeds directly into automated replenishment cycles, minimizing markdowns and out-of-stock rates.
Competitor Analysis: Technical and Financial Comparison
Fast Retailing’s primary global competitors are Inditex(Spain) and H&M Group(Sweden).
| Metric / Dimension | Fast Retailing(Uniqlo) | Inditex(Zara) | H&M Group |
| Core Value Proposition | Functional, high-durability essentials(“LifeWear”) | Rapid trend responsiveness & runway replication | Mass-market accessible fashion variety |
| Annual Revenue(FY24/25) | ~¥3.1T–¥3.4T(~$21B–$22B USD) | ~€38.6B(~$41B–$42B USD) | ~SEK 236B(~$21.8B USD) |
| Operating Margin | ~15%–18% | ~18%–19% | ~7%–8% |
| Product Cycle / Lead Time | Long cycle(6–12 months); high-volume functional basics | Ultra-fast cycle(2–4 weeks); small initial batch runs | Medium cycle(4–8 weeks); balanced trend/basic mix |
| Supply Chain Footprint | Concentrated in Asia(China, Southeast Asia); high batch size | Nearshoring in Iberia/Turkey/Morocco(~50%); dynamic logistics | Widely dispersed across Asia and Southern Europe |
Technical & Operational Comparison:
- Fast Retailing prioritizes material science and SKU rationalization over rapid design iteration. It uses fewer SKUs but produces them in massive volumes, refining technical fabric performance year after year.
- Inditex relies on localized production agility and algorithm-driven trend analytics, producing limited runs to induce artificial scarcity and keep markdown rates minimal.
- Fast Retailing’s technical edge lies in automated warehousing, universal RFID implementation, and upstream synthetic fiber chemistry, whereas Inditex excels in short-haul logistics and agile distribution scheduling.
Financial Comparison:
- Fast Retailing maintains a strong balance sheet with high cash balances and operating margins(15%+), significantly outperforming H&M’s mid-single-digit margins, while approaching Inditex’s profitability.
- Inditex generates superior inventory turnover and asset turnover due to nearshoring, but Fast Retailing benefits from lower unit production costs and strong pricing discipline on functional basics.
Information Sources
- https://www.fastretailing.com/eng/ir/direction/position.html
- https://www.fastretailing.com/tc/ir/financial/
- https://www.economyinsights.com/p/top-10-apparel-companies-by-market-cap
- https://bestcolorfulsocks.com/blogs/news/fast-fashion-revenue-statistics
- https://en.wikipedia.org/wiki/Fast_Retailing
back to Fast Retailing