
Market Position and Market Share
Bridgestone Corporation ranks as the second-largest tire manufacturer globally, positioned right behind France’s Michelin and ahead of Goodyear, Continental, and Pirelli.
- Global Ranking: #2 in worldwide tire-related revenue.
- Market Share: Bridgestone commands approximately 13.5% to 14.5% of the global tire market by sales value, while Michelin holds roughly 14.5% to 15.5%, Goodyear controls approximately 9% to 10%, and Continental holds around 6.5% to 7.5% (estimates based on global automotive tire industry sales volume and value tracked by Tire Business rankings).
- Revenue Scale: For FY2024, Bridgestone reported consolidated global revenue of approximately 4.43 trillion JPY (approximately $28.9 billion USD), with pure tire-manufacturing sales totaling approximately $24.77 billion USD.
- Regional Dominance: Bridgestone holds leading positions in North America (via Bridgestone Americas/Firestone), Japan, and the Asia-Pacific region, while maintaining strong competitive reach across Europe and Latin America. It holds market-leading shares in high-rim-diameter passenger car tires (≥18 inches) and ultra-large mining off-the-road (OTR) tires.
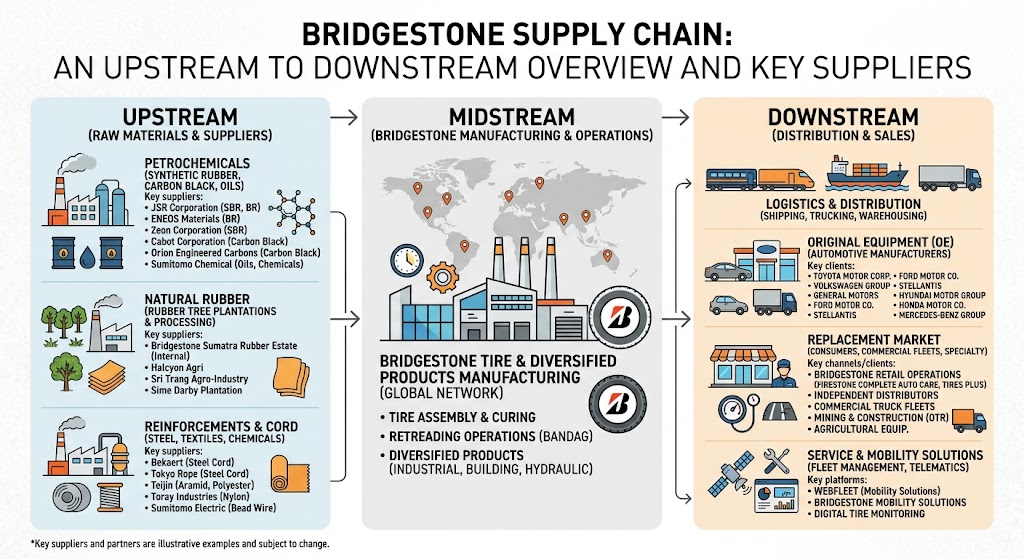
Upstream and Downstream Supply Chain Analysis & Key Suppliers
1. Upstream (Raw Materials & Manufacturing Equipment)
Tire production requires a balance of raw polymers, reinforcing materials, and specialized processing chemicals:
- Natural Rubber (NR): Represents approximately 20% to 25% of tire weight and a significant portion of raw material costs. Bridgestone secures supply through its proprietary rubber plantations in Southeast Asia (such as Indonesia, including P.T. Bridgestone Sumatra Rubber Estate) alongside third-party sourcing across Thailand, Indonesia, and Vietnam. It also invests heavily in guayule research in the Southwestern United States as an alternative natural rubber source.
- Synthetic Rubber (SR): Comprising styrene-butadiene rubber (SBR) and polybutadiene rubber (BR) derived from butadiene/petrochemical feedstocks. Key commercial suppliers include petrochemical majors such as JSR Corporation, ENEOS Materials, Zeon Corporation, Kumho Petrochemical, and Asahi Kasei.
- Reinforcing Agents & Fillers:
- Carbon Black: Crucial for structural reinforcement, abrasion resistance, and tensile strength. Key external suppliers include Cabot Corporation, Orion Engineered Carbons, Birla Carbon, and Tokai Carbon.
- Precipitated Silica & Silane Coupling Agents: Essential for low rolling resistance and wet grip in EV and green tires. Major suppliers include Evonik Industries, Solvay, and PPG Industries.
- Cords & Reinforcement Materials:
- Steel Cord & Bead Wire: Provides internal structural rigidity. Sourced from players like Bekaert and Tokyo Rope.
- Textile Cords (Polyester, Rayon, Aramid): Sourced from specialized synthetic fiber suppliers such as Teijin, Toray Industries, and Hyosung.
- Manufacturing Machinery & Automation: High-precision curing presses, calendar lines, and extrusion units supplied by specialized equipment builders such as Kobelco (Kobe Steel) and Mitsubishi Heavy Industries Machinery.
2. Downstream (Sales Channels & End Markets)
Bridgestone’s downstream distribution flows through two distinct avenues:
- Original Equipment (OE):
- Accounts for roughly 20% to 30% of tire unit volume. Bridgestone works directly as a Tier-1 partner with global automotive OEMs, including Toyota, Honda, Nissan, General Motors, Ford, Stellantis, BMW, Mercedes-Benz, and Volkswagen.
- Direct co-development is standard for vehicle-specific OE homologations, with tailored compounds for battery electric vehicles (BEVs) to handle higher curb weights and immediate torque.
- Replacement Market (Aftermarket):
- Accounts for approximately 70% to 80% of operating profit due to higher pricing power and recurring demand cycles.
- Distribution channels include company-owned retail networks (e.g., Bridgestone Retail Operations operating over 2,200 stores in the U.S. under Firestone Complete Auto Care, Tires Plus, and Wheel Works), franchised dealerships, independent tire distributors, wholesale chains, and commercial fleet service centers.
- Specialty & Fleet Solutions (B2B):
- Large OTR tires for mining and construction equipment (supplying Caterpillar, Komatsu, and global mining conglomerates).
- Commercial fleet management and telematics platforms (e.g., Webfleet/Bridgestone Mobility Solutions) delivering digital tire monitoring and retread services (Bandag) directly to transport fleets.
Competitor Analysis: Technology & Financials
Bridgestone operates in an oligopoly dominated by the “Tier 1” trio (Michelin, Bridgestone, Goodyear) alongside Continental and Pirelli.
1. Technology Comparison
- EV Optimization & Tire Architecture:
- Bridgestone: Centers its approach on ENLITEN technology, a modular architecture that reduces rolling resistance, cuts raw material usage, and lowers tire weight by up to 20% while maintaining tread life. It pairs this with B-Silent noise-reduction foam to address electric cabin acoustics.
- Michelin: Deploys Acoustic Technology and specialized compounds engineered for instant torque and higher mass, leveraging its market-leading position in premium EV OE homologations (e.g., Porsche, Tesla).
- Continental & Pirelli: Continental incorporates ContiSilent and EcoContact/SportContact platforms. Pirelli concentrates exclusively on the high-end luxury/EV tier with its dedicated Elect marking (featured heavily on Lucid, Porsche Taycan, and high-performance trims).
- Airless & Non-Pneumatic Tires:
- Bridgestone continues field evaluations of its Air Free Concept for micro-mobility, light commercial, and planetary exploration vehicles (in collaboration with JAXA for lunar rovers). Michelin is in advanced road trials with its UPTIS (Unique Puncture-proof Tire System) in partnership with delivery fleets like DHL and GM.
- Digital Fleet Solutions & Telematics:
- Bridgestone’s acquisition of Webfleet gives it direct telematics access to commercial fleets, combining tire sensor telemetry with logistics routing. Michelin counters with Michelin Connected Fleet and Camso integrations, while Goodyear deploys Goodyear SightLine predictive maintenance algorithms.
- Specialty Mining & Off-The-Road (OTR):
- Bridgestone and Michelin form an effective duopoly in 57-inch and 63-inch ultra-large radial mining tires, where Bridgestone’s specialized compounds and master service agreements provide substantial barriers to entry.
2. Financial Comparison
| Metric / Dimension | Bridgestone | Michelin | Goodyear | Continental (Tire Div.) |
| Annual Revenue | ~$28.9B USD (~4.43T JPY) | ~$29.5B USD (~27.2B EUR) | ~$18.5B USD | ~$15.0B USD (~14.0B EUR) |
| Operating Margin | ~10.5% – 11.5% | ~12.0% – 13.0% | ~4.0% – 6.0% | ~11.0% – 12.5% |
| Capital Structure & Leverage | Very low debt-to-equity; net cash/low gearing; conservative Japanese balance sheet. | Low-to-moderate leverage; strong investment-grade rating (A-/A3). | Highly leveraged post-Cooper Tire acquisition; undergoing aggressive asset divestitures. | Moderately leveraged; protected cash flows within the broader automotive group. |
| Cost Structure & Margin Drivers | High exposure to raw material fluctuation and JPY/USD currency shifts; ongoing European capacity restructuring. | Premium price-over-cost realization; superior pricing power in 18″+ replacement tires. | Higher North American labor/manufacturing cost base; restructuring non-core units (e.g., Dunlop, Off-highway). | Highly automated European footprint; efficient procurement synergies with automotive divisions. |
| Free Cash Flow Generation | Highly steady (~250B-350B JPY annually); dedicated to dividends and selective Capex. | Robust cash conversion (~1.5B-2.0B EUR annually); disciplined shareholder distributions. | Constrained by elevated debt-service obligations and operational restructuring cash outlays. | Dependable cash flow generator serving as an internal profit cushion for parent Continental AG. |
- Profitability & Pricing Power: Michelin consistently edges out Bridgestone in adjusted operating margin by 100 to 200 basis points due to its premium brand equity and higher average selling price (ASP). Bridgestone remains more profitable than Goodyear by a wide margin, benefiting from operational discipline, automation in Japan, and high-margin OTR mining exposure.
- Balance Sheet Resilience: Bridgestone operates with one of the most conservative balance sheets among global industrial manufacturers, maintaining a low debt profile and strong cash reserves, whereas Goodyear continues to manage elevated financial leverage resulting from its Cooper Tire acquisition.
Sources
- https://www.bridgestone.com/ir/library/result/pdf/e_r6_4_4_presentation.pdf
- https://www.bridgestone.com/ir/library/result/pdf/e_r6_4_4_results.pdf
- https://www.moderntiredealer.com/suppliers/news/55269063/bridgestone-posts-full-year-2024-results
- https://finance.sina.com.cn/wm/2025-10-28/doc-infvkumz1557135.shtml
- https://tyresourcing.com/global-tire-manufacturers/
- https://www.michelin.com/en/finance/results-and-sales/
- https://corporate.goodyear.com/us/en/investors/financial-reports.html
back to Bridgestone