
Market Position and Market Share
BPER Banca S.p.A.ranks as the 4th largest commercial banking group in Italy by total assets, solidifying its place right behind Intesa Sanpaolo, UniCredit, and Banco BPM following its aggressive multi-year M&A consolidation (including carved-out branches from UBI Banca, the acquisition of Banca Carige, and the takeover of Banca Popolare di Sondrio).
- Total Assets & Balance Sheet Scale: Total assets stand at approximately €140 billion to €146 billion on an organic basis (expanding past €200 billion upon consolidated pro-forma integration of recent banking acquisitions).
- Domestic Market Share: Holds an estimated national market share of 4.4% to 5.0% in customer deposits and total loans across Italy. Regional density is significantly higher in its core operational strongholds: Emilia-Romagna (where market share exceeds 10%–12%), Sardinia (via subsidiary Banco di Sardegna, holding local market leadership exceeding 30%), and Liguria (via the acquired Carige footprint).
- Network & Reach:Serves approximately 5 million customers across 18 of Italy’s 20 regions through a network of roughly 1,600 branches.
Upstream and Downstream Supply Chain Analysis
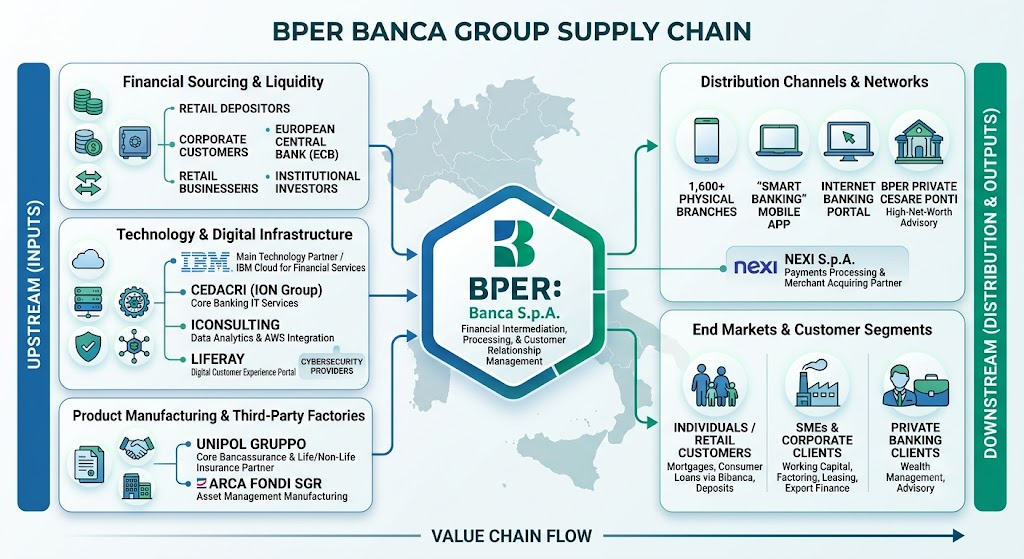
Because BPER Banca operates as a commercial banking and wealth management institution rather than a manufacturing entity, its supply chain functions as a financial intermediation and technological infrastructure pipeline:
- Upstream Supply Chain (Capital Sourcing, Technology, and Product Factories):
- Capital & Liquidity Inflows: Retail deposits from households, corporate operating accounts, institutional wholesale debt (senior preferred/non-preferred paper, covered bonds), and European Central Bank (ECB) targeted liquidity facilities.
- Key IT & Infrastructure Suppliers:Core technology infrastructure and hybrid cloud modernization are led by IBM (via IBM Cloud for Financial Services and IBM Consulting under multi-year modernization pacts), IT services and systems integration by Cedacri (ION Group), enterprise data analytics by Iconsulting (leveraging AWS), and digital customer journey portal systems by Liferay.
- Product Factories & Bancassurance: Life and non-life insurance underwriting is primarily supplied by anchor shareholder Unipol Gruppo (holding a 19.9% stake). Asset management manufacturing is driven through its ownership in Arca Fondi SGR.
- Payments & Clearing Infrastructure: Card issuing and merchant acquiring processing outsourced in a long-term strategic partnership to Nexi S.p.A..
- Downstream Supply Chain (Distribution Channels & Customer Segments):
- Direct Distribution Network:An omnichannel branch network combined with the “Smart Banking” mobile and web banking apps, supported by specialized private banking advisory centers under brand names such as BPER Private Cesare Ponti.
- Target End-Markets: Italian Small and Medium Enterprises (SMEs) represent the foundational loan and transaction base (export financing, working capital, factoring, leasing), followed by residential mortgage borrowers, consumer credit clients (via Bibanca), and high-net-worth individuals.
Competitor Analysis: Financial and Technological Comparison
BPER Banca competes primarily within the Italian banking arena against tier-1 giants (Intesa Sanpaolo, UniCredit) and direct mid-tier peers (Banco BPM, Banca Monte dei Paschi di Siena [MPS]).
| Metric / Dimension | BPER Banca | Intesa Sanpaolo | Banco BPM | UniCredit |
| Domestic Scale & Role | 4th largest domestic Italian commercial bank | #1 domestic Italian bank; undisputed market leader | 3rd largest Italian bank; dense northern industrial focus | #2 in Italy; pan-European systemic bank (Italy, Germany, CEE) |
| P/E (TTM) Multiple | ~11x–13x | ~7x–9x | ~6x–8x | ~7x–9x |
| Return on Tangible Equity (RoTE) | ~13%–16% | ~15%–18% | ~13%–15% | ~16%–19% |
| CET1 Ratio | ~15.8%–16.2% | ~13.5%–14.0% | ~14.2%–14.8% | ~15.9%–16.2% |
| Asset Quality (Gross NPE Ratio) | ~2.6%–3.0% (Substantially cleaned via bad loan derisking) | ~2.3%–2.6% | ~3.3%–3.5% | ~2.7%–2.8% |
| Cost-to-Income Ratio | ~46%–51% | ~41%–43% | ~48%–50% | ~39%–41% |
- Financial Comparison:
- Capital Strength & Resilience: BPER boasts a very solid Common Equity Tier 1 (CET1) ratio of around 15.8%–16.2%, standing comfortably above regulatory minimums and rivaling UniCredit while exceeding Intesa’s balance sheet buffering.
- Efficiency & Returns: BPER operates at a lean cost-to-income ratio (~46%–51%), though Intesa and UniCredit maintain superior operating leverage due to massive pan-European scale and higher non-interest fee revenue generation.
- Technological Comparison:
- Architecture & Digital Capabilities: Unlike Intesa Sanpaolo—which built its proprietary cloud-native digital banking platform (Isybank) with Thought Machine—BPER relies on hybrid modernization via IBM Cloud for Financial Services and modular integration layers.
- Execution Agility: BPER has demonstrated exceptional operational capability in integrating multiple core banking platforms in rapid succession (migrating UBI carved-out branches, Carige systems, and partner platforms onto unified Group systems) without major customer service disruptions.
- Fintech & Open Banking Integration:While larger competitors build in-house neo-banking platforms, BPER relies on strategic partnerships (e.g., Nexi for digital payments, Webidoo and Gility for SME client digital transformation tools) to deliver digital-first services.
Sources
- https://thebanks.eu/countries/Italy/major_banks
- https://en.wikipedia.org/wiki/BPER_Banca
- https://group.bper.it/documents/d/bper-istituzionale/bper-company-profile-2025-1h2025-eng
- https://newsroom.ibm.com/2022-10-27-BPER-Banca-Group-Collaborates-with-IBM-to-Modernize-Core-Banking-Systems-and-Accelerate-Digital-Transformation-Plan
- https://www.spglobal.com/market-intelligence/en/news-insights/articles/2025/1/italys-biggest-banks-set-to-report-higher-profits-for-2024-87209783
- https://www.globaldata.com/company-profile/bper-banca-spa/
- https://www.gurufocus.com/stock/MIL:BPE/summary
Back to BPER