
Market Position and Market Share
ASR Nederland N.V. (a.s.r.) ranks as the #2 overall insurer in the Netherlands by Gross Written Premium (GWP) and balance sheet assets, positioned directly between market leader NN Group and non-life specialist Achmea. Following the transformational acquisition of Aegon’s Dutch business activities (completed in 2023 and fully integrated by mid-2026), a.s.r.cemented its dominant position across key segments:
- Disability Insurance (AOV/WIA):Ranked #1 in the Dutch market, holding an estimated ~30% to 35% market share. It serves as the primary provider of occupational disability protection for both individual entrepreneurs (ZZP) and group employer schemes.
- Pensions and Defined Contribution (DC):Ranked #1/#2 (competing neck-and-neck with NN Group). Combining Aegon Cappital (PPI) and a.s.r. pension administration elevated DC assets under management to over €27 billion, capturing roughly ~25% to 28% of the addressable commercial pension market.
- Property & Casualty (P&C / Non-Life):Ranked #2/#3 (trailing Achmea and rivaling NN Group). Its non-life portfolio (excluding health) accounts for approximately ~16% to 18% market share, further reinforced by bolt-on acquisitions such as automotive specialist Bovemij.
- Life Insurance (Traditional In-Force):Ranked #2 behind NN Group, commanding approximately ~22% to 25% of Dutch life technical reserves.
Supply Chain Upstream/Downstream Analysis and Key Suppliers
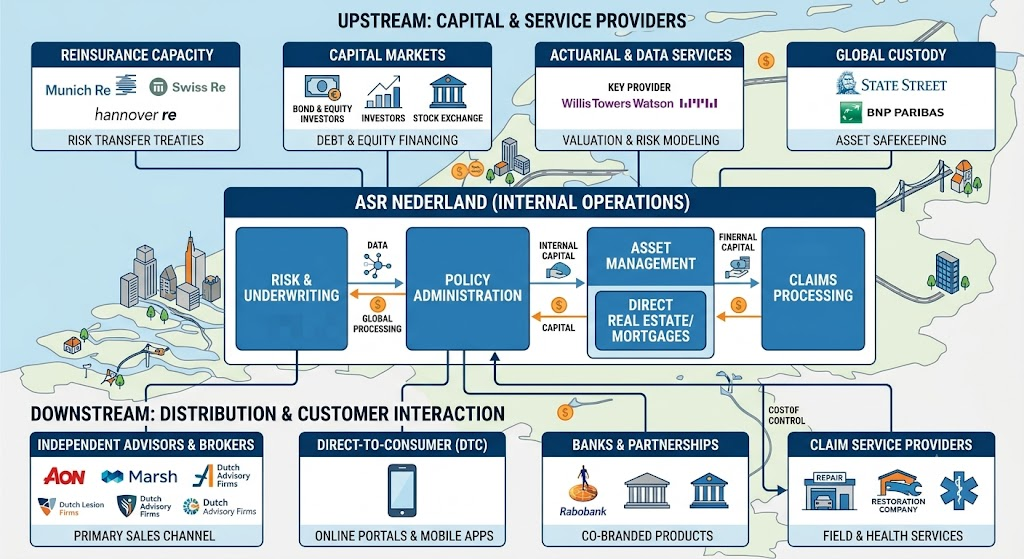
In the financial services and insurance sector, the “supply chain” functions as an ecosystem spanning capital, underwriting capacity, core processing infrastructure, claims servicing, and distribution networks.
1. Upstream (Capital, Risk Underwriting, and Tech Infrastructure)
- Reinsurance Capacity Providers: To absorb extreme catastrophe risks (e.g., European windstorms, hail, large-scale commercial property fire) and manage Solvency II capital relief, a.s.r. relies heavily on Tier-1 global reinsurers. Key counterparties include Munich Re, Swiss Re, and Hannover Re. These reinsurers provide quota-share treaties, excess-of-loss protection, and specialized longevity risk-transfer structures.
- Core Systems and Cloud Architecture Providers:
- Policy Administration & Actuarial Engines: Key core system providers include Keylane (deploying the Axon platform for Non-Life and Life policy administration) and specialized actuarial modeling suites from FIS (Prophet) and Moody’s Analytics for Solvency II balance sheet modeling.
- Cloud & Enterprise Infrastructure: Core operations run primarily on Microsoft Azure and Amazon Web Services (AWS) for scalable data warehousing, real-time analytics, and customer portals.
- Data & Financial Intelligence:Bloomberg, FactSet, and MSCI ESG supply benchmark pricing, asset data, and sustainability metrics for proprietary balance sheet investments.
- Investment Management and Custody:While a.s.r. manages its core real estate and mortgage funds in-house (a.s.r. Real Estate), long-term asset management agreements tied to the Aegon transaction involve Aegon Asset Management. Global asset custody is handled by institutions such as BNP Paribas Securities Services and State Street.
2. Downstream (Distribution Channels and Claims Fulfillment)
- Intermediary Distribution (Key B2B Channel): Unlike direct-only digital players, a.s.r. relies extensively on an omni-channel approach with a heavy reliance on independent financial advisors (IFAs), brokers, and managing general agents (Volmachten). Intermediaries drive over 65% of commercial lines and complex disability policies. Key aggregator/broker networks include Aon, Marsh McLennan, and nationwide Dutch franchise advisory networks.
- Direct & White-Label Distribution: Digital direct channels operate under brands like Ditzo (now integrated) and Knab (banking distribution partnership).
- Claims Fulfillment & Repair Networks: For P&C automotive and property claims, down-chain execution depends on contracted restoration firms (e.g., Polygon Nederland for water/fire remediation) and certified vehicle repair networks (e.g., Schadenet, ABS Autoherstel), ensuring fixed-tariff cost containment.
Competitor Analysis: Technical and Financial Comparison
The Dutch market is an oligopoly dominated by three primary domestic giants: ASR Nederland, NN Group, and Achmea.
1. Financial Profile Comparison
- Capital Discipline & Solvency II Resilience: a.s.r. operates with one of the most resilient balance sheets in Europe, posting a Solvency II ratio of 222%, compared to NN Group’s ~200% and Achmea’s ~190%. Its balance sheet is heavily fortified by local Dutch residential mortgage assets, which feature low credit default rates and attractive risk-weighted capital treatment under Solvency II.
- Underwriting Profitability:a.s.r. consistently beats peers on Non-Life combined ratio performance. Its P&C and Disability combined ratio hovers between 91.0% and 92.5%, outperforming NN Group (94-95%) and Achmea (whose heavy basic health insurance exposure operates near break-even).
- Organic Capital Creation (OCC):a.s.r.’s capital engine produces roughly €1.35B+ in annual OCC, facilitating steady mid-to-high single-digit progressive dividend increases and recurring share buyback programs.
2. Technical and Operational Comparison
- Legacy Consolidation Engine vs. Multi-Country IT Debt: a.s.r. possesses an operational track record as a specialist integrator. By acquiring and migrating books from Generali Nederland (2018), Loyalis (2019), and Aegon Nederland (2023–2026), it systematically migrates target policies onto standardized SaaS architectures (e.g., Keylane Axon), decommissioning target mainframe systems to achieve targeted run-rate cost synergies. In contrast, NN Group must balance IT modernization across Central Eastern European units and legacy Dutch portfolios.
- Data-Driven Underwriting in Disability (AOV): a.s.r.’s primary technical edge lies in occupational disability risk pricing and return-to-work rehabilitation protocols. By combining granular actuarial health data with integrated workplace reintegration services, it maintains lower claims duration compared to competitors.
- Asset-Liability Matching (ALM):Both a.s.r. and NN Group employ sophisticated dynamic interest-rate hedging swaption portfolios to match long-dated Dutch pension liabilities. However, a.s.r. maintains higher operational agility due to its concentrated exposure on the Dutch sovereign, mortgage, and direct property markets.
Sources
- https://www.asrnl.com/investor-relations
- https://www.asrnederland.nl/investor-relations
- https://www.asrnl.com/-/media/files/asrnederland-nl/investor-relations/jaarverslagen/2025/2025-annual-report-asr.pdf
- https://www.asrnl.com/-/media/files/asrnederland-nl/investor-relations/jaarverslagen/2024/2024-asr-nederland-nv-sfcr.pdf
- https://www.aegon.com/investors/information-on-combination
- https://www.spglobal.com/ratings/en/regulatory/article/-/view/type/HTML/id/3440055
- https://www.investing.com/news/company-news/asr-nederland-h1-2026-slides-record-occ-222-solvency-ratio-93CH-4866684
- https://research.ing.com/repos/F8159191-1210-4214-8F7F-0C5D074BFF2A.pdf
Back to ASR Nederland