
Market Position and Market Share
Ageas is a multinational insurance group headquartered in Brussels, Belgium, listed on Euronext Brussels (ticker: AGS) and a constituent of the benchmark BEL20 index.The group manages both Life and Non-Life operations, alongside an expanding internal and third-party reinsurance franchise.In fiscal year 2025, Ageas generated €19.6 billion in total gross inflows (a 9% increase year-on-year at constant exchange rates), delivered a net operating result of €1.655 billion, and achieved a Group net result of €1.712 billion.
- Belgium (Core Domestic Market):Ageas operates through AG Insurance, where it holds the undisputed #1 position with approximately 30% to 33% market share in Life insurance and roughly 16% to 17% in Non-Life insurance.AG Insurance provides insurance coverage to almost 1 out of every 2 Belgian households and serves over 3 million customers. In 2025, gross inflows in Belgium reached €5.615 billion, generating a net operating result of €497 million. Ageas formalized an agreement to acquire the remaining 25% minority stake in AG Insurance from BNP Paribas Fortis for €1.9 billion, bringing its ownership to 100%.
- United Kingdom: Ageas UK historically ranked among the top 10 personal lines underwriters, with a focus on private motor and home coverage. Following the strategic acquisitions of esure and Acromas (Saga’s underwriting arm), Ageas propelled itself to the #3 position in the UK personal lines insurance market, providing coverage to more than 4 million vehicles and policyholders.
- Continental Europe and Türkiye:
- Portugal: Ageas Seguros and Médis establish Ageas as the #2 Life insurer and the #1 market leader in private Health insurance through the Médis managed healthcare brand.
- Türkiye: Operating via joint ventures with Sabancı Holding, AgeSa ranks #2 in Life insurance and is the leading private pension provider in Türkiye, while Aksigorta operates as a major non-life carrier.
- Asia (High-Growth Partnerships):Ageas operates across 9 Asian countries (including China, Malaysia, Thailand, India, the Philippines, and Vietnam) through structured joint ventures, serving approximately 27.5 million customers.
- China:Through a long-standing 24.9% equity stake in Taiping Life and a 10% stake in Taiping Pension (which added €10.9 billion in pension assets under management), Ageas captures extensive distribution scale via China Taiping Insurance Group. Asian operations contributed €8.699 billion in inflows and €860 million to net profit in 2025.
- Thailand & Malaysia: Ageas partners with Kasikornbank/Muang Thai Life (ranking #2 in the Thai life insurance market) and Maybank in Malaysia (Etiqa, leading conventional and Takaful provider).
- Reinsurance (Ageas Re): Launched as a standalone reinsurance carrier, Ageas Re writes internal group quota shares and external third-party risks across more than 50 countries. External third-party reinsurance inflows reached €905 million in 2025, operating with an underwriting combined ratio of 76.5%.
Supply Chain Upstream, Downstream, and Key Suppliers
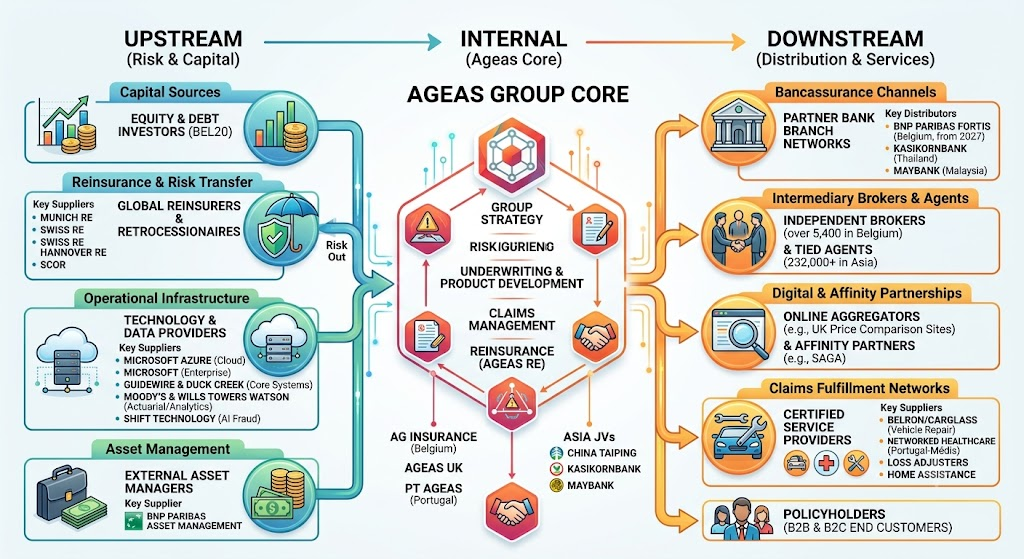
In the financial services and insurance sector, the supply chain is structured around capital inputs, risk transfer, technology infrastructure, distribution networks, and claims service fulfillment.
Upstream (Risk Transfer, Capital & Core Service Providers)
- Reinsurance & Retrocession Providers: While Ageas Re absorbs internal underwriting exposures, Ageas retrocedes peak catastrophic property, flood, and personal injury liabilities to global reinsurance counterparties. Its key tier-1 reinsurance counterparties include Munich Re, Swiss Re, Hannover Re, and SCOR. On the inward reinsurance side, Ageas acts as an upstream capacity provider for insurtechs, such as its quota-share agreement with Italian digital auto insurer Prima (generating €630 million in inflows).
- Asset Management & Financial Custody: Investment returns are a primary source of underwriting margins. Following the full acquisition of AG Insurance, Ageas structured a long-term asset management collaboration with BNP Paribas Asset Management to manage designated fixed-income and alternative asset portfolios. Internal asset liability management (ALM) teams govern real estate assets, including infrastructure holdings like Interparking.
- Actuarial Modeling, IT & Cloud Infrastructure Providers:
- Cloud Computing & Enterprise Software: Microsoft (Azure cloud architecture, enterprise collaboration, and AI integrations).
- Core Insurance & Policy Administration Engines: Guidewire Software and Duck Creek Technologies provide underwriting, policy life-cycle, and billing platforms for European and UK subsidiaries.
- Actuarial & Regulatory Analytics: Moody’s Analytics (RiskIntegrity) and Willis Towers Watson (RiskAgility, Igloo) supply the mathematical engines used to calculate Solvency II capital requirements and IFRS 17 contractual service margins (CSM).
- Fraud Detection & Data Analytics: Shift Technology (AI-based claims fraud detection), alongside regional telematics data providers for motor insurance telemetry.
Downstream (Distribution Channels, B2B2C Partners & Claims Networks)
- Bancassurance Networks: Long-term bancassurance contracts serve as Ageas’s primary distribution channel. In Belgium, Ageas operates a exclusive 15-year distribution partnership with BNP Paribas Fortis (starting 2027), distributing life, savings, and general insurance products across banking branches. In Asia, distribution relies on bank branch footprints provided by Kasikornbank in Thailand and Maybank in Malaysia.
- Intermediary Brokers & Tied Agent Networks: In Belgium, AG Insurance works with an open network of over 5,400 licensed, independent brokers. In Asia, products are distributed through an affiliated sales force exceeding 232,000 tied agents across regional joint ventures.
- Digital Aggregators & B2B2C Affinity Partnerships: In the UK market, personal auto and home lines depend on digital price comparison websites (PCWs), including Compare the Market, Go.Compare, Confused.com, and MoneySuperMarket. Specialized affinity channels include a distribution partnership with Saga Services to underwrite over-50s policies. In emerging markets like India, Ageas deploys API-integrated B2B2C embedded platforms.
- Claims Fulfillment & Service Networks: Downstream claims execution is supported by certified networks of collision repair facilities, vehicle glass replacement specialists (e.g., Belron/Carglass), emergency home assistance providers, loss adjusters, and Médis’s direct network of private clinics and hospitals in Portugal.
Competitor Analysis: Technical and Financial Comparison
Ageas competes against integrated pan-European insurers, domestic bancassurers, and local incumbents across its operational regions.
- Primary Competitors:
- Belgium & Benelux:KBC Group, AXA Belgium, Ethias, Baloise Belgium, and Belfius Insurance.
- United Kingdom: Admiral Group, Aviva, and Direct Line Group.
- Pan-European & Global: Allianz SE, AXA Group, and Generali.
- Asia:Ping An Insurance, China Life, AIA Group, and Prudential plc.
Technical and Operational Capabilities
- Underwriting Architecture and Dynamic Pricing: In personal lines motor underwriting, Ageas UK utilizes a dynamic pricing engine powered by machine learning algorithms that calculate real-time risk scores on digital broker and aggregator platforms. While this matches modern pricing standards, pure-play direct competitors like Admiral Group retain a data edge in proprietary telematics scoring and long-term customer behavioral tracking.
- AI Deployment and Automation: Ageas has operationalized over 300 active AI and Generative AI use cases across customer service, automated claims intake, and predictive agency productivity. In contrast to global rivals like Allianz (which utilizes the centralized Allianz Business System) and AXA, Ageas operates a federated IT architecture due to its multi-entity joint venture structure, resulting in higher localized customization but slower global core system homogenization.
- Digital Customer Integration: Domestic rival KBC holds a market advantage in Belgium through its proprietary digital assistant (Kate), which natively combines everyday retail banking with instant insurance cross-selling. Ageas compensates for this by pairing its broker network with direct digital interfaces and leveraging BNP Paribas Fortis’s digital mobile banking platform.
Financial Comparison
| Metric (FY 2025 / Latest) | Ageas Group | Allianz SE | AXA Group | KBC Group (Insurance) |
| Total Inflows / Gross Written Premiums | €19.60B | €170B+ | €105B+ | €4.0B+ |
| Non-Life Combined Ratio | 92.5% | ~92.8% | ~91.5% | 87.0% |
| Solvency II Ratio | 211% (195% in H1 2026) | 218% | 215% (estimated range) | 201% |
| Return on Equity (ROE) | 19.3% | ~15.5% | ~14.8% | ~16.0% (Group) |
| Net Result / Net Profit | €1.71B (€1.65B Operating) | €10.0B+ | €7.5B+ | €1.16B (Group Net) |
- Underwriting Discipline:Ageas improved its non-life combined ratio to 92.5% in 2025 (down from 93.6% in 2024), reflecting resilience against severe weather events across Belgium and Portugal. While KBC achieved a lower combined ratio (87.0%) within its localized bank-insurance network, Ageas matched the global combined ratios of multi-line giants Allianz (~92.8%) and AXA (~91.5%).
- Capital Solvency:Ageas maintains a Solvency II ratio of 211% at year-end 2025 (moderating to 195% in H1 2026 due to the capital deployment for the Taiping Pension transaction and the acquisition of AG Insurance’s remaining shares).This places its capital buffer in line with Allianz (218%) and AXA (~215%).
- Profitability and Capital Generation: Ageas produced a Return on Equity (ROE) of 19.3% in 2025, outperforming the European insurance peer group median (typically 13% to 16%). This outperformance was driven by high cash upstream from its Asian joint ventures (notably in China and Thailand) combined with stable life margin releases under IFRS 17.
Information Sources
- https://www.ageas.com/en/about-us/activities
- https://ageas.com/en/annual-report-2025
- https://ageas.com/en/annual-report-2024
- https://www.ageas.com/en/newsroom/ageas-to-take-full-ownership-of-ag-insurance-and-formalise-long-term-partnership-with-bnp-paribas-3201192
- https://www.reinsurancene.ws/ageas-achieves-9-rise-in-net-inflows-in-2025-as-reinsurance-expansion-continues/
- https://www.investing.com/news/company-news/ageas-h1-2026-slides-resilient-profit-cash-guidance-raised-49-93CH-4878613
- https://www.asquarepartners.com/en/results-2025-be/
- https://assets.ctfassets.net/o6mf177wvfka/6IkQRHbSSfbgMvoZ4dhrSE/aea6df1a2dea4e552f5aca8ef368d802/EN_Results_FY25_003_25022026.pdf
Back to Ageas