Market Position and Market Share
CK Hutchison Holdings Limited(00001.HK)is one of the world’s largest multinational conglomerates, operating across roughly 50 countries with over 300,000 employees globally. The company maintains dominant global and regional market positions across four core pillars:
- Ports and Related Services(Hutchison Ports):Ranks as the world’s #4 container terminal operator by throughput, handling approximately 85–90 million TEU in gross throughput and over 47 million TEU on an equity-adjusted basis across 53 ports in 24 countries. It commands roughly 10%–11% of global port operator throughput, trailing only PSA International, China Merchants Port, and COSCO Shipping Ports.
- Retail(A.S. Watson Group): Operates the world’s largest international health and beauty retail network with over 16,500 stores across 28 markets in Asia and Europe. It ranks #14 on the NRF Top 50 Global Retailers List, holding the #1 or #2 market share position in health and beauty across core European markets(Superdrug in the UK, Kruidvat in the Benelux, Rossmann joint venture in Germany)and Greater China/Southeast Asia(Watsons).
- Infrastructure(CK Infrastructure Holdings – 1038.HK): Owns and manages critical regulated utility networks spanning energy, water distribution, and transportation across the UK, Continental Europe, Australia, New Zealand, and Canada. Its regulated assets(e.g., UK Power Networks, Northumbrian Water)provide inflation-linked, monopolistic utility cash flows.
- Telecommunications(CK Hutchison Group Telecom / 3 Group): Serves over 100 million active mobile customers across Europe and Asia. Following the high-profile merger of 3 UK with Vodafone UK, the combined VodafoneThree entity commands a leading ~35% subscriber share in the UK mobile market, while CKHGT maintains strong market share across Italy(Wind Tre), Sweden, Austria, and Ireland.
Supply Chain Architecture and Key Suppliers
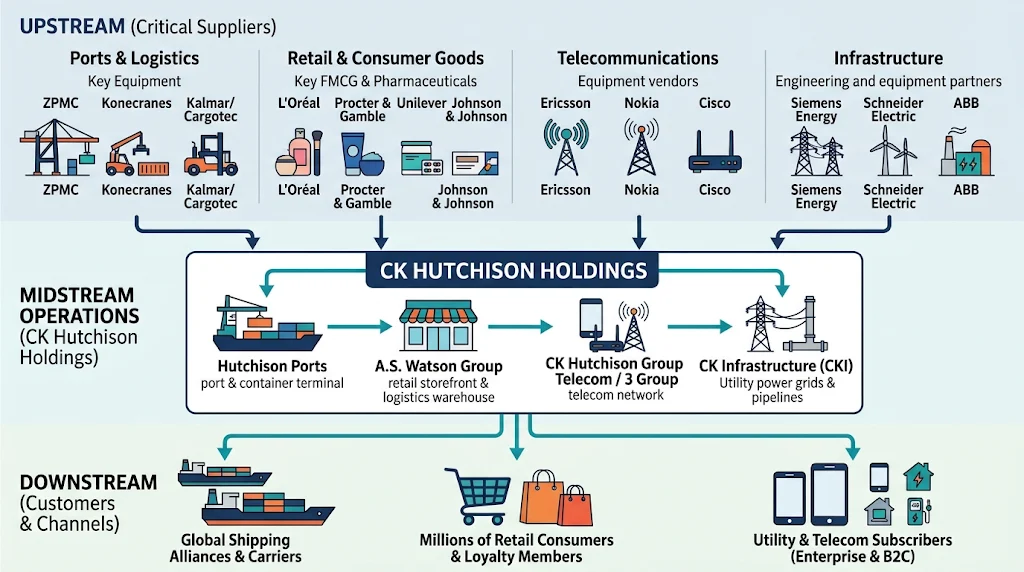
Because CK Hutchison is a diversified multinational conglomerate, its supply chain flows across specialized infrastructure, technology, procurement, and logistics layers:
- Upstream(Capital Equipment, Wholesale Merchandising, & Tech Infrastructure):
- Retail Division: Sources tens of thousands of SKUs from global Fast-Moving Consumer Goods(FMCG)and pharmaceutical giants, alongside proprietary contract manufacturing. Key suppliers include L’Oréal, Procter & Gamble, Unilever, Johnson & Johnson, Haleon, and Beiersdorf.
- Ports Division: Relies on heavy port-handling machinery, gantry cranes, and terminal automation software. Key critical equipment suppliers include Shanghai Zhenhua Heavy Industries(ZPMC), Konecranes, and Cargotec/Kalmar.
- Telecom Division: Sources Radio Access Network(RAN)gear, core network routing, fiber backhaul, and 5G equipment. Key network infrastructure vendors include Ericsson, Nokia, and Cisco, while handset vendors include Apple, Samsung, and Xiaomi.
- Infrastructure Division: procures turbine and power transmission grid hardware, gas pipeline infrastructure, and water filtration equipment from engineering conglomerates like Siemens Energy, Schneider Electric, and ABB.
- Midstream(Value Creation & Asset Operation):
- Global terminal handling, yard management, vessel berthing, and bonded logistics.
- O+O(Offline plus Online)retail supply chain logistics, high-density automated distribution centers, inventory replenishment, and customer loyalty management.
- Mobile core network operations, spectrum management, mast infrastructure, data centers, and multi-cloud connectivity.
- Downstream(Off-Takers, Customers, and B2B/B2C Channels):
- Global ocean carrier shipping alliances(Ocean Alliance, Gemini Cooperation, Premier Alliance, MSC)and freight forwarders for terminal services.
- Over 160 million loyalty members and retail consumers across Europe and Asia.
- Enterprise clients, mobile virtual network operators(MVNOs), and retail telecom subscribers.
Competitor Analysis: Technical and Financial Comparison
CK Hutchison competes with dedicated category leaders across each operational vertical as well as legacy global conglomerates.
Technical & Strategic Positioning Comparison
- Ports vs. PSA International & DP World:
- Technology & Automation: PSA leads the industry in automated guided vehicle(AGV)deployment and mega-terminal integration at Tuas Port. DP World has vertically integrated upstream into end-to-end digital freight forwarding(e.g., Imperial Logistics, syncreon). Hutchison Ports distinguishes itself through proprietary terminal operating systems(nGen)and automated remote-controlled quay cranes(RCQC), emphasizing multi-gateway efficiency across high-volume trade lanes.
- Retail vs. Walgreens Boots Alliance & Sephora(LVMH):
- Omnichannel Strategy: While Walgreens Boots Alliance has struggled with debt and physical store footprints in the US, A.S. Watson pioneered the “O+O”(Offline plus Online)platform model. Sephora dominates the premium prestige beauty segment, whereas Watson’s brand portfolio spans accessible mass-market pharmacy and personal care(Watsons, Kruidvat, Superdrug)with proprietary private-label margins exceeding 30%.
- Telecom vs. Deutsche Telekom, Orange, & Vodafone:
- Network Scale & Asset Monetization: Pure-play incumbents like Deutsche Telekom enjoy pan-European scale and dominant fixed-mobile convergence(FMC). CK Hutchison has actively restructured its European mobile portfolio—monetizing passive tower assets through a multibillion-euro sale to Cellnex and merging 3 UK with Vodafone UK to achieve market scale and eliminate sub-scale CapEx duplication.
Financial Metrics Comparison
| Financial Metric | CK Hutchison(00001.HK) | Jardine Matheson(J36.SI) | DP World / Global Port Peers | Walgreens Boots Alliance(WBA) |
| Business Model | Diversified Conglomerate | Diversified Pan-Asian Conglomerate | Dedicated Marine Terminal Operator | Pure-Play Pharmacy & Beauty Retail |
| Annual Revenue | ~HK$480B–HK$507B (~US$62B–$65B) | ~US$36B–$38B | ~US$14B–$18B | ~US$145B |
| EBITDA Margin | ~24%–26% | ~14%–16% | ~30%–35% | ~3%–5% |
| Operating Margin | ~9.2%–11.5% | ~6.5%–8.0% | ~18%–22% | ~0.5%–2.0% |
| Free Cash Flow | >HK$30B (Strong, resilient cash generation) | Moderate | Capital intensive | Pressured by restructuring |
| Leverage Profile | Conservative; strong investment-grade balance sheet (Net debt / EBITDA < 2.5x) | Conservative | Moderate to High | High leverage |
CK Hutchison maintains a superior defensive financial structure compared to single-sector competitors. Its capital allocation combines regulated, counter-cyclical utility distributions with recurring retail cash flows, shielding the balance sheet from shipping downcycles and telecom spectrum bidding wars.
Sources
- https://www.ckh.com.hk/tc/global/home.php
- https://www1.hkexnews.hk/listedco/listconews/sehk/2024/0419/2024041900568.pdf
- https://www.ckh.com.hk/upload/attachments/en/pr/e_CKHH_AR_2025_full_20260319.pdf
- https://blog.gettransport.com/trends-in-logistic/largest-port-operators-world-2026-ranked/
- https://imperiumcs.com/commodity-markets/products/shipping-freight/ports-terminals-maritime-infrastructure/
- https://185-anniversary.aswatson.com/latest-news/as-watson-ranked-among-the-world-s-top-15-retailers
- https://pitchgrade.com/companies/ck-hutchison-holdings-ltd
back to CK Hutchison