
Company History
Phase 1: Cooperative Roots and Emilia-Romagna Foundations (1867–1991)
The bank traces its origin to 1867 with the founding of Banca Popolare di Modena, established as a mutual cooperative bank to finance local merchants and small agricultural producers. In 1992, Banca Popolare di Modena merged with Banca Cooperativa di Bologna to form Banca Popolare dell’Emilia Romagna (BPER), laying the groundwork for multi-regional cooperative banking.
Phase 2: Federal Expansion Across Italian Regions (1994–2014)
Throughout the 1990s and 2000s, BPER adopted a federal banking structure, acquiring regional credit institutions across southern and central Italy, including Banco di Sardegna and Banca di Sassari. This model allowed acquired entities to retain regional brand autonomy while centralizing risk management and IT administration at the group holding level in Modena.
Phase 3: Corporate Reform and Structural Modernization (2015–2019)
In response to the 2015 Italian banking reform mandating large cooperative lenders to abandon mutual status, BPER transformed from a società cooperativa into a joint-stock company (società per azioni / S.p.A.) in 2016. In 2017, the bank marked its 150th anniversary by acquiring Cassa di Risparmio di Ferrara (Carife), initiating active restructuring and non-performing loan securitization.
Phase 4: Transformational M&A and National Consolidation (2020–Present)
BPER expanded its national market share dramatically through opportunistic acquisitions. In 2021, it acquired 486 branches and 134 operational units divested from Intesa Sanpaolo following Intesa’s takeover of UBI Banca. In 2022, BPER completed the acquisition and statutory absorption of Banca Carige, solidifying its position as Italy’s third-largest banking force and restructuring under the leadership of major shareholder Unipol Gruppo and CEO Gianni Franco Papa.
Business Model and Strategy
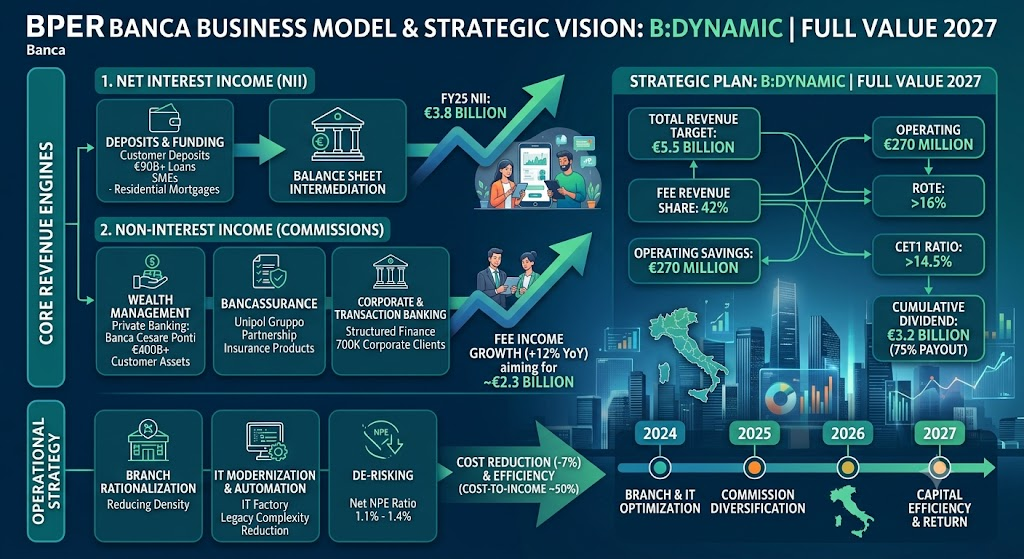
BPER Banca generates revenue primarily through two core mechanisms: net interest income (NII) from balance-sheet intermediation, and non-interest fee/commission income from wealth management, corporate advisory, and bancassurance distribution.
- Net Interest Margin Monetization: The core earnings engine relies on lending ~€90 billion to €97 billion in gross customer loans (weighted toward SMEs and residential mortgages) financed by low-cost retail current accounts and commercial deposits. Net interest income reached ~€3.8 billion in FY25.
- Wealth Management and Bancassurance Factory: Under its private banking arm (Banca Cesare Ponti) and asset-management operations, BPER monetizes €400+ billion in total customer financial assets. Net commission income contributes ~€2.0 billion to €2.3 billion annually, driven by wealth management fees (+10.3% YoY in 1H26) and distribution margins from insurance products manufactured via its strategic partnership with Unipol Gruppo.
- Corporate & Transaction Banking: Monetizes specialized corporate services, including structured finance, export credit, foreign exchange hedging, and working capital solutions across ~700,000 corporate clients.
Strategic Plan: “B:Dynamic | Full Value 2027”
Under the 2024–2027 strategic framework, BPER is shifting from asset expansion to capital efficiency and fee-driven diversification to counter declining interest rates:
- Targeting €5.5 Billion in Revenues by 2027: Offsetting €450 million in projected NII headwinds by expanding commission income (+12% or +€550 million by 2027, reaching ~42% of total revenue).
- Operational Restructuring: Reducing absolute operating costs by 7% (-€270 million pre-inflation) through branch rationalization and back-office automation, targeting a cost-to-income ratio around 50% by 2027 (and heading toward ~40% under the 2028 acceleration lever).
- Capital Return and Balance Sheet Hygiene: Targeting a return on tangible equity (ROTE) exceeding 16%, cumulative dividend distributions of ~€3.2 billion (average payout ratio of ~75%), a CET1 ratio above 14.5%, and maintaining net NPE at ~1.4%.
Sources for Business Model and Financial Data
- https://group.bper.it/en/bper-group/business-plan
- https://group.bper.it/documents/133577364/2790717168/24.10.10+B:Dynamic+Full+Value+2027
- https://group.bper.it/documents/133577364/2790290452/24.10.10+BPER+CMD_def_ENG.pdf/3f4247ae-3622-f961-8c01-ef980bb481a5
- https://group.bper.it/en/investor-relations/presentations
- https://group.bper.it/documents/d/bper-istituzionale/bper-banca-4q25-fy25-results-presentation
AI Strategy, Budget, and Technology Partnerships
Technology & AI Budget
Under the 2024–2027 strategic plan, BPER allocated approximately €650 million in dedicated IT capital expenditure (CapEx) to establish the “IT Factory of the Future”. This budget represents a steep increase from the previous cycle (€210 million) to fund end-to-end digital modernization, cybersecurity resilience, and group-wide generative AI deployment.
Implementation Architecture and Concrete Use Cases
BPER’s AI strategy focuses on three operational layers to drive an estimated €300 million in cumulative operational savings and a 15% increase in relationship-manager productivity:
- Front-Office Advisor Copilots: Equipping wealth advisors and commercial relationship managers with AI-driven co-pilots for real-time portfolio optimization, automated client profiling, and next-best-action recommendations across the branch and digital network.
- End-to-End Credit & Back-Office Automation: Implementing agentic AI workflows across mortgage underwriting, SME credit assessment, and document processing. Automated classification algorithms handle know-your-customer (KYC) onboarding and anti-money laundering (AML) pattern checks, reducing manual processing cycles.
- Internal Data Science Labs & “Up-Skilling Factory”: Establishing a dual model where central Data Science Labs under the Chief Data Officer coordinate Citizen Data Scientists across business units to build specialized fine-tuned models. The bank committed to up-skilling ~30% of its full-time equivalent (FTE) workforce in digital tools and AI workflows.
Key Strategic Partners and Infrastructure
- IBM: BPER operates under a multi-year enterprise transformation agreement with IBM Consulting to modernize core banking systems using the IBM Cloud for Financial Services, Red Hat OpenShift, and mainframe z16 architectures. This infrastructure acts as the secure foundation for hosting regulated, low-latency AI software capabilities and omnichannel services.
- Salesforce: Integrated across group-wide CRM operations to ingest multichannel customer data and power predictive marketing models for loan and bancassurance cross-selling.
AI Governance and Compliance
BPER was among the first Italian financial institutions to formalize a dedicated “Group Regulation on the Ethics and Governance Process of Artificial Intelligence Systems”. Aligned directly with the European Union AI Act, this governance charter enforces mandatory risk categorization (from minimal risk to high-risk AI), algorithmic auditability, and formal human-in-the-loop (HITL) and human-in-command (HIC) operational constraints for all underwriting and predictive decision engines.
Back to BPER