
Latest Financial Earnings Summary
Ipsen reported its financial results for the first half of 2026 (covering the second quarter and six-month period ending June 30, 2026):
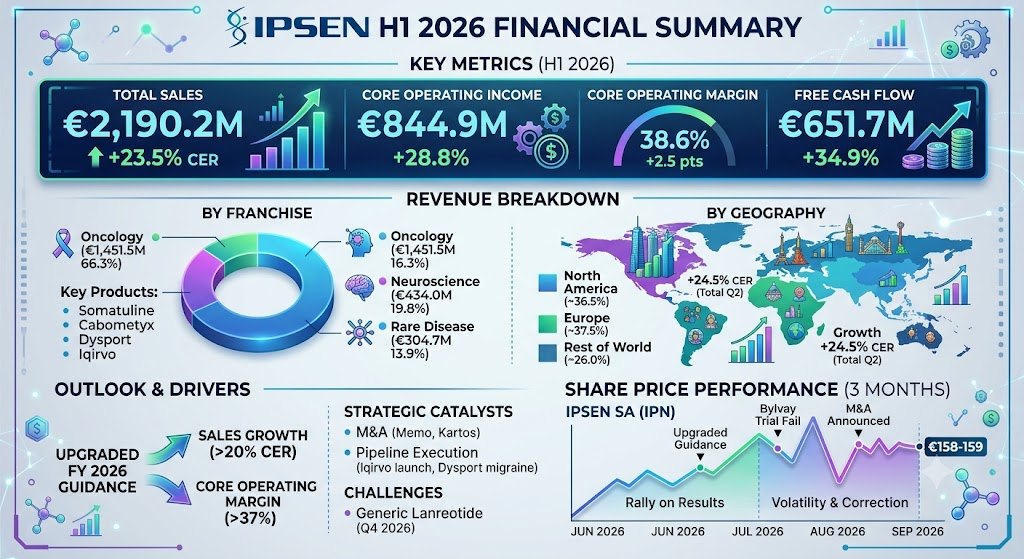
- Total Sales:Reached €2,190.2 million in H1 2026, up 20.4% as reported and 23.5% at constant exchange rates (CER).Second-quarter (Q2 2026) sales reached €1,115.3 million, up 23.8% as reported and 24.5% at CER.
- Core Operating Income:Rose 28.8% to €844.9 million, compared to €655.8 million in H1 2025.
- Core Operating Margin:Expanded by 2.5 percentage points to 38.6% of total sales.
- Core Net Profit & EPS:Core consolidated net profit rose 19.6% to €607.7 million, with fully diluted core earnings per share (EPS) growing 20.7% to €7.33 (IFRS net profit was €402.6 million, up 20.0%).
- Cash Flow & Balance Sheet:Free cash flow increased 34.9% to €651.7 million, bringing the closing net cash position to €1,004.9 million as of June 30, 2026.
Revenue Breakdown by Therapeutic Segment and Geography
Therapeutic Franchise & Product Breakdown (H1 2026 Total Sales: €2,190.2 million)
- Oncology Franchise (€1,451.5 million, 66.3% of total sales; +15.6% CER):
- Somatuline (€686.3 million, 31.3% of sales; +21.0% CER): A somatostatin analog indicated for acromegaly and gastroenteropancreatic neuroendocrine tumors (GEP-NETs). It grew strongly due to favorable demand and supply shortages/delays among generic lanreotide competitors.
- Cabometyx (€350.5 million, 16.0% of sales; +18.8% CER):A multi-kinase inhibitor marketed outside the US for advanced renal cell carcinoma (RCC), hepatocellular carcinoma (HCC), and neuroendocrine tumors.
- Decapeptyl (€284.3 million, 13.0% of sales; +3.5% CER):A GnRH agonist primarily prescribed for locally advanced or metastatic prostate cancer, endometriosis, and precocious puberty.
- Onivyde (€108.0 million, 4.9% of sales; +11.2% CER): Encapsulated irinotecan liposome injection indicated for metastatic pancreatic ductal adenocarcinoma.
- Ojemda & Other Oncology (€22.4 million, 1.0% of sales): Driven by the early launch of Ojemda (tovorafenib) for pediatric low-grade glioma (€14.5 million).
- Neuroscience Franchise (€434.0 million, 19.8% of total sales; +16.6% CER):
- Dysport Aesthetics (€257.4 million, 11.8% of sales; +19.6% CER): Botulinum toxin type A distributed for glabellar lines and facial aesthetic procedures.
- Dysport Therapeutics (€170.0 million, 7.8% of sales; +13.8% CER): Formulated for therapeutic indications including spasticity and cervical dystonia.
- Other Neuroscience (€6.6 million, 0.3% of sales): Legacy neurology products.
- Rare Disease Franchise (€304.7 million, 13.9% of total sales; +108.0% CER):
- Iqirvo (€173.3 million, 7.9% of sales; +209.7% CER): First-in-class dual PPAR alpha/delta agonist (elafibranor) approved for primary biliary cholangitis (PBC), capturing substantial switch and naive patient share in the US and Europe.
- Bylvay (€120.3 million, 5.5% of sales; +44.8% CER): An ileal bile acid transporter (IBAT) inhibitor for progressive familial intrahepatic cholestasis (PFIC) and Alagille syndrome (ALGS).
- Other Rare Disease (€11.1 million, 0.5% of sales): Including Sohonos (palovarotene) for fibrodysplasia ossificans progressiva (FOP).
Geographical Revenue Breakdown
- Europe (~37.5% of total sales, ~€820 million):Anchored by solid Cabometyx volume growth (spurred by neuroendocrine tumor launches in Germany) and stable hospital demand for Somatuline and Decapeptyl.
- North America (~36.5% of total sales, ~€800 million): The fastest-growing major region, powered by rapid commercial adoption of Iqirvo, expanding Bylvay sales, and Somatuline market resilience.
- Rest of the World (~26.0% of total sales, ~€570 million):Driven by double-digit expansion of Dysport aesthetics in Latin America and the Asia-Pacific region, alongside growing Decapeptyl volumes in China and initial launches of Bylvay in Japan.
Operational Changes, Catalysts, and Future Outlook
Key Operational Developments & Pipeline Changes
- Upgraded FY 2026 Guidance:Ipsen raised its full-year 2026 constant-currency sales growth guidance from >13.0% to >20.0%, and raised its core operating margin target from >35.0% to >37.0%.
- Somatuline Generic Delay:Expected generic lanreotide launches in North America faced production hurdles, pushing major generic pressure out to late Q4 2026 and driving a 21.0% CER surge in Somatuline sales.
- Strategic External Innovation (M&A):
- Completed the acquisition of Memo Therapeutics AG in July 2026 for €200 million upfront (up to €700 million total) to secure potravitug.
- Completed the acquisition of Kartos Therapeutics in August 2026 for $450 million upfront (plus up to $1.3 billion in contingent milestones) to acquire navtemadlin (MDM2 inhibitor).
- Clinical Trial Outcomes:Dysport achieved positive Phase III readouts in the C-BEOND and E-BEOND trials for chronic and episodic migraine.Iqirvo met its primary endpoint in the Phase III ELSPIRE trial for PBC.Conversely, Bylvay’s Phase III BOLD trial in biliary atresia failed its primary endpoint of native liver survival in July 2026.
Next-Quarter Observation Points & Future Outlook
- Generic Lanreotide Entry in Q4 2026: Monitoring market share and pricing resilience of Somatuline as generic suppliers re-enter distribution channels.
- Iqirvo Commercial Trajectory: Evaluating whether US conversion rates stabilize and observing the pace of commercial reimbursement rollouts across major EU member states.
- Regulatory Milestones & Pipeline Execution:Preparing regulatory submissions for Dysport in migraine, progressing elafibranor Phase III in primary sclerosing cholangitis, and initiating Phase II/III studies for navtemadlin.
Three-Month Share Price Performance and Drivers
Share Price Movement (June 2026 – September 2026)
- Trading Range: Shares of Ipsen (Euronext Paris: IPN) opened June 2026 at €151.80, rallied through late June and reached a peak of €170.70 in early July 2026. Following pipeline updates and broader European equity swings in late July and August, the stock consolidated between €155.00 and €169.00, trading around €158.50 to €159.20 by early September 2026 (representing a modest 3-month gain of ~4.4%).
Market Drivers Behind Price Action
- Upward Momentum (June – Early July):The stock rallied on accelerating non-Somatuline sales momentum, exceptional early commercial data for Iqirvo, and anticipation of an upgraded 2026 financial guidance.
- Mid-Summer Volatility & Correction (Late July – August):
- Clinical Trial Setback: On July 24, 2026, Ipsen announced that the Phase III BOLD trial of Bylvay in biliary atresia missed its primary endpoint, dampening expansion expectations for that indication.
- Somatuline Overhang & Broker Revisions: On August 3, 2026, Jefferies downgraded Ipsen to “Underperform”, warning that despite strong H1 results, the eventual arrival of generic lanreotide in late 2026 poses medium-term revenue cliffs for Somatuline.
- M&A Integration Costs: The upfront cash outflows for Memo Therapeutics (€200m) and Kartos Therapeutics ($450m) led investors to factor in near-term R&D dilution.
Sources
- https://www.ipsen.com/press-release/ipsen-delivers-excellent-h1-2026-results-and-upgrades-its-full-year-guidance-3335743/
- https://ml-eu.globenewswire.com/Resource/Download/b44435a8-36ee-477f-b9a2-c6e3db5e9c2c
- https://www.ipsen.com/press-release/ipsen-delivers-strong-sales-in-the-first-quarter-of-2026-and-confirms-its-full-year-guidance-3279554/
- https://scanx.trade/stock-market-news/companies/ipsen-h1-results-sales-rise-23-5-at-cer-guidance-upgraded/46933764
- https://www.investing.com/news/company-news/ipsen-h1-2026-slides-rare-disease-surges-guidance-upgraded-93CH-4824746
- https://www.stockopedia.com/share-prices/ipsen-sa-EPA:IPN/
Back to Ipsen