
Market Position and Market Share
NN Group(Euronext: NN)is a leading financial services corporation with a dominant presence in Europe, particularly within the Netherlands and Central and Eastern Europe(CEE). In its core Dutch market, NN Group ranks as the #1 domestic non-life insurer by gross written premiums(holding approximately 28% to 30% market share following the consolidation of Delta Lloyd and Vivat Non-Life)and the #2 life insurer(holding approximately 22% to 25% market share, competing directly with aSR). Across the broader Dutch pension market, it holds the leading position in defined contribution(DC)schemes. In Central and Eastern Europe—notably Poland, the Czech Republic, Slovakia, Hungary, and Romania—NN ranks among the top 3 life and pension providers, controlling over 15% to 20% of the private pension and life insurance markets in key jurisdictions such as Poland and the Czech Republic. In asset management, following the €1.7billion divestment of NN Investment Partners to Goldman Sachs in 2022, NN Group maintains an integrated capital allocation model managing approximately €150billion+ in insurance-related balance-sheet assets.
Upstream and Downstream Supply Chain Analysis and Key Suppliers
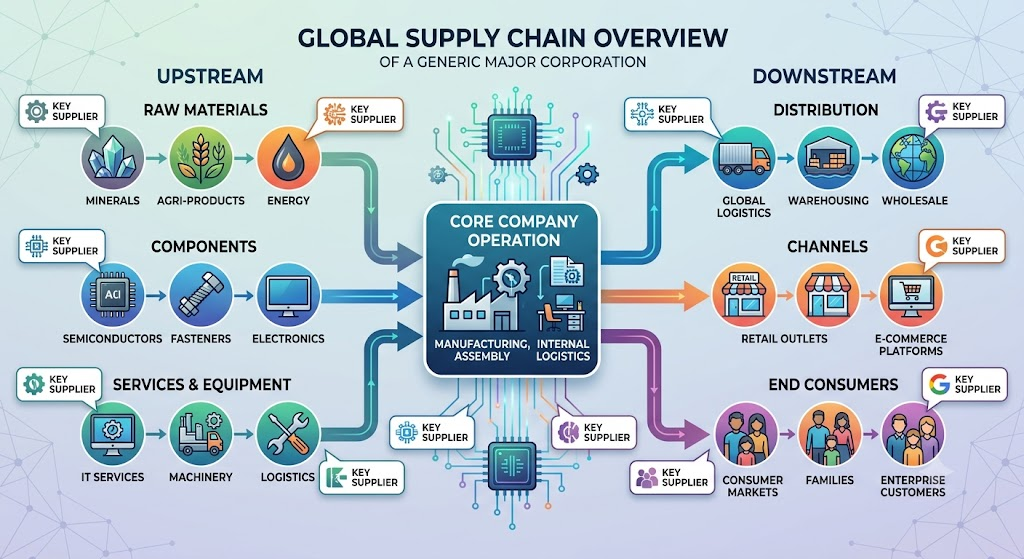
The operational supply chain of an integrated insurer and asset owner consists of capital sourcing, reinsurance, technology/data procurement(upstream)and diversified distribution channels(downstream).
- Upstream Supply Chain:
- Reinsurance & Risk Transfer: To mitigate systemic underwriting risk and manage solvency capital requirements under Solvency II, NN Group partners upstream with top-tier global reinsurers. Key counterparties include Munich Re, Swiss Re, Hannover Re, and SCOR. These counterparties absorb catastrophe risk(particularly European windstorms and regional flooding)and mortality/longevity risk.
- IT, Cloud Infrastructure & Core Platforms: Upstream digital transformation relies heavily on hybrid cloud infrastructure and policy-administration platforms. Critical enterprise vendors include Microsoft(Azure cloud infrastructure and workplace systems), Amazon Web Services(AWS for analytics and digital platforms), and specialized insurance core system vendors such as Keylane and Guidewire for claims and policy administration.
- Financial Market Infrastructure & Data Feeds: Upstream market risk management, statutory reporting, and investment operations rely on mission-critical data and clearing providers including Bloomberg LP, FactSet, MSCI(for ESG indexing and benchmark tracking), and custodians such as State Street and BNY Mellon.
- Downstream Supply Chain:
- Distribution Networks: Downstream distribution is segmented by geography and product vertical. In the Netherlands, retail non-life and life products rely heavily on independent financial advisors(IFAs), corporate brokers(such as Aon and Marsh McLennan), and proprietary direct-to-consumer digital channels(Nationale-Nederlanden and OHRA).
- Bancassurance Partnerships: Across Central Europe and international markets, downstream customer acquisition is driven by strategic tied-agent sales forces and long-term bancassurance agreements with regional retail banks(such as ING Bank and local retail banking networks in Poland and Romania).
Competitor Analysis
NN Group’s primary competitive field is divided between domestic Dutch champions and pan-European multi-line conglomerates.
- Primary Competitors: aSR Nederland(core Dutch rival), Aegon/transferred to aSR(following the 2023 transaction where aSR acquired Aegon’s Dutch operations while Aegon took a 29.99% strategic stake in aSR), Allianz SE, and AXA.
- Technical & Operational Comparison:
- Capital & Solvency Architecture: NN Group operates with an internal capital generation model yielding Solvency II ratios consistently around 195%–215%, reflecting strong capital resilience. Following aSR’s acquisition of Aegon Nederland, aSR has achieved scale comparable to NN Group in domestic non-life and disability insurance. However, NN Group maintains superior cross-border diversification due to its high-margin CEE life and protection franchise, whereas aSR remains almost exclusively concentrated in the Netherlands.
- Underwriting & Cost Discipline: NN Group’s Property & Casualty(P&C)combined ratio typically operates in the 93%–96% range, benefiting from automated claims processing and direct digital underwriting via OHRA. aSR maintains an equally disciplined combined ratio(often 92%–94%)due to deep domestic broker relationships and specialized disability insurance underwriting.
- Digitalization & Product Breadth: NN Group possesses advanced capabilities in digital retail banking through NN Bank(primarily a mortgage-origination vehicle funding domestic assets)and online retail protection. In contrast, pan-European peers like Allianz and AXA leverage massive scale in proprietary AI risk-modeling algorithms, but lack the domestic market entrenchment NN holds in the Dutch defined contribution pension space.
- Financial Comparison:
- Operating Capital Generation(OCG): NN Group generates robust OCG exceeding €1.7billion to €1.9billion annually, driving capital return programs(dividends and multi-hundred-million-euro share buybacks).
- Return on Equity(ROE): NN Group targets and sustains an operating ROE in the 12%–15% range, outpacing broader European multi-line averages(typically 10%–13%)due to its asset-light CEE protection businesses.
- Leverage & Debt Servicing: NN Group maintains a financial leverage ratio between 20% and 23%, with fixed-income hybrid debt structures providing strong interest coverage(over 10x), matching the balance sheet quality of AA-rated international peers.
Sources
- https://www.nn-group.com/investors.htm
- https://www.nn-group.com/our-company.htm
- https://www.asrnl.com/investor-relations
- https://www.dnb.nl/en/statistics/data-search/#/
Back to NN Group