
Latest Financial Results Summary
Bank of Ireland published its interim financial results for the first half of 2026(6 months ended June 30, 2026), reporting strong momentum across balance sheet expansion, wealth assets, and profitability:
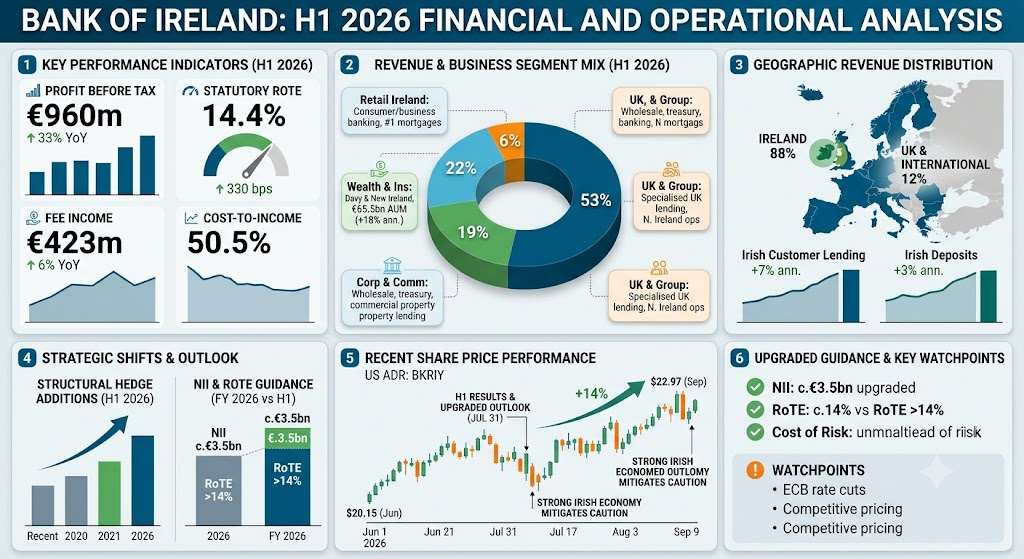
- Profit Before Tax(PBT): €960m, increasing by 33% year-over-year.
- Earnings Per Share(EPS): Rose 36% year-over-year.
- Statutory Return on Tangible Equity(RoTE): Reached 14.4%, up from 11.1% in H1 2025.
- Net Interest Income(NII): €1.7bn, up 2% year-over-year, driven by balance sheet growth and structural hedge contributions offsetting rate headwinds.
- Fee Income: Totaled €423m, rising 6% year-over-year, buoyed by the Wealth and Insurance franchises(Davy and New Ireland).
- Total Costs(excluding levies): €1.08bn, up 2% year-over-year, delivering a disciplined Cost-to-Income Ratio(CIR) of 50.5%.
- Asset Quality: Net credit impairment charge stood at €32m(8bps cost of risk); the Non-Performing Exposure(NPE) ratio improved to 2.0%(compared to 2.2% at December 2025).
- Capital and Distributions: Pro forma CET1 capital ratio reached 15.5%, supported by 135bps of organic capital generation. An interim ordinary dividend of €0.39 per share was announced, representing a 56% year-over-year increase with a 50% payout ratio.
Revenue Breakdown by Division and Geography
Segment Breakdown
Bank of Ireland reports its operational performance across three primary operating divisions alongside Group Centre functions:
- Retail Ireland(c. 50-55% of total income): Serves consumer and micro-business segments across Ireland. Products include residential mortgages, personal lending, current accounts, deposits, and digital daily banking. The bank maintains the #1 position in Irish residential mortgages.
- Wealth and Insurance(c. 15-20% of total income): Comprises New Ireland Assurance and Davy(wealth management and capital markets). Offers life insurance, pensions, investment products, asset management, and corporate broking. Fee income in this segment grew 11% year-over-year, with Assets Under Management(AUM) expanding 18% annualized to a record €65.5bn.
- Corporate and Commercial(c. 20-25% of total income): Provides lending, transaction banking, foreign exchange, treasury, and advisory services to mid-to-large corporates, commercial property clients, and specialized international sectors.
- Retail UK & Group Centre(c. 5-10% of total income): Encompasses Northern Ireland full-service operations, UK mortgage portfolios, and strategic partnership lending(e.g., Post Office/AA), alongside central treasury and funding allocations.
Geographic Breakdown and Regional Developments
- Ireland(Republic of Ireland – c. 85-90% of total income): Remains the group’s core growth engine. Supported by strong domestic economic growth, low national debt-to-GDP, favorable demographics, and high household net worth. Irish customer lending expanded by 7% annualized, while Irish customer deposits expanded by 3% annualized during H1 2026.
- United Kingdom & International(c. 10-15% of total income): Retail UK continues to experience planned deleveraging and asset optimization. Loan volumes and UK deposits trended lower in line with management’s selective capital deployment strategy focusing on risk-adjusted margins rather than volume pursuit.
Quarterly and Semi-Annual Shifts, Key Watchpoints, and Strategic Outlook
Recent Portfolio and Balance Sheet Shifts
- Structural Hedge Expansion: During July 2026, the group added c. €8bn to its structural hedge to build resilience against European Central Bank(ECB) interest rate cuts.
- Liquidity and Bond Assets: Liquid assets reached €46.4bn, while the euro bond portfolio expanded to €23.0bn(from €20.0bn at December 2025). Liquidity coverage ratio stood at 191%, and loan-to-deposit ratio remained balanced at 77%.
- Credit Risk Normalization: Net credit impairment remained subdued at €32m(cost of risk: 8bps), with Stage 2 credit volumes and default rates declining.
Key Watchpoints for Upcoming Quarters
- Structural Hedge Reinvestment Yields: How reinvestment dynamics will protect margins as European central bank monetary easing takes effect.
- Mortgage and Deposit Competition: Competitive pricing pressures from domestic peers in fixed-rate mortgages and savings accounts.
- Davy and New Ireland Net Inflows: Tracking whether organic AUM additions sustain the 18% annualized momentum seen in H1.
- Cost Inflation Management: Monitoring operating expenses against the €2.2bn FY26 cap in the face of wage pressures.
Future Outlook and Upgraded Guidance
Management raised its official financial guidance for FY2026 and reiterated medium-term targets out to 2028:
- Full-Year 2026 NII: Upgraded to c. €3.5bn(previously c. €3.4bn); medium-term trajectory targeted at c. €3.75bn in FY2027 and >€3.95bn in FY2028.
- Full-Year 2026 RoTE: Upgraded to >14%(previously 12.5%).
- Full-Year 2026 Capital Generation: Projected at c. 270bps.
- Cost of Risk: Expected in the mid-to-high teens basis points range(lowered from low-to-mid 20s bps).
- Total Costs: Reaffirmed at c. €2.2bn(+2% growth y/y).
Share Price Performance Over the Past 3 Months
Over the past three months(June to early September 2026), Bank of Ireland Group shares(Euronext Dublin: BIRG / US OTC: BKRIY) demonstrated positive momentum:
- Price Movement: US ADRs(BKRIY) rose from around $20.15 in mid-June 2026 to $22.97 by September 9, 2026, representing an appreciation of approximately 14.0%. Dublin-listed shares similarly climbed from the €18.50-€18.80 range toward €19.90-€20.00.
- Market Drivers:
- Earnings and Guidance Beats: The release of H1 2026 interim results on July 31, 2026 delivered an upgraded full-year outlook for NII(to €3.5bn) and RoTE(>14%), triggering immediate institutional buying.
- Accelerated Capital Returns: A 56% increase in the interim dividend to €0.39 per share affirmed management’s payout confidence.
- Macro Resilience: Resilient Irish economic indicators and controlled credit impairment mitigated broader macroeconomic and geopolitical caution across European equities.
Information Sources
- https://investorrelations.bankofireland.com/app/uploads/2026-H1-RNS-FINAL-N-P.pdf
- https://www.investing.com/news/transcripts/earnings-call-transcript-bank-of-ireland-lifts-2026-outlook-after-strong-h1-93CH-4826950
- https://www.investing.com/equities/bank-ireland-historical-data
- https://www.londonstockexchange.com/news-article/BIRG/bank-of-ireland-interim-results-29-july-2025/17155909
back to Bank of Ireland