
Latest Quarterly Financial Results Summary
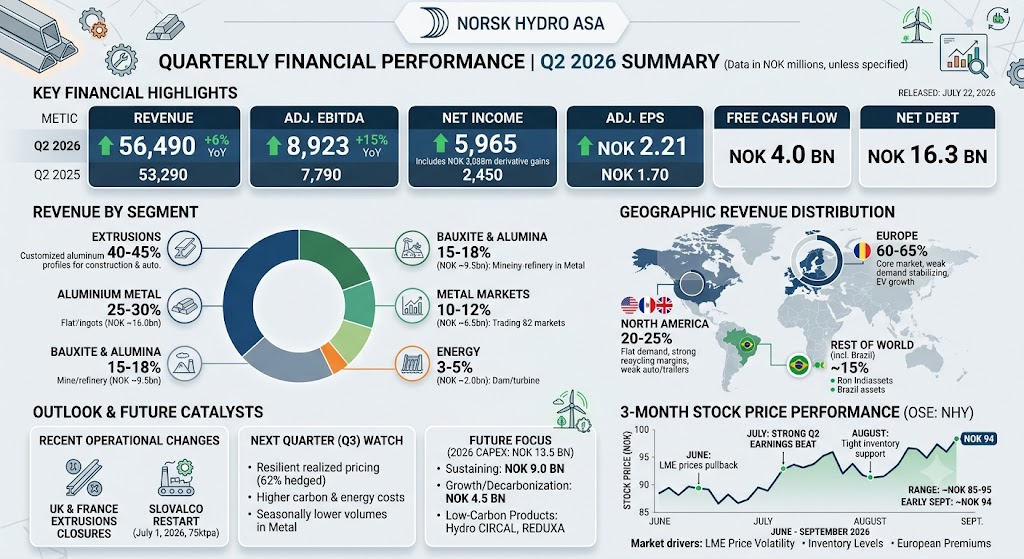
Norsk Hydro ASA published its Q2 2026 financial report on July 22, 2026, delivering solid operational performance driven by higher metal prices and resilient recycling operations:
- Revenue:NOK 56.49 billion, up 6% YoY.
- Adjusted EBITDA:NOK 8,923 million, up 15% YoY compared to NOK 7,790 million in Q2 2025.
- Net Income: NOK 5,965 million, up significantly from NOK 2,450 million in Q2 2025, supported by derivative gains of NOK 3,088 million on LME contracts.
- Adjusted Earnings Per Share(EPS):NOK 2.21, compared to NOK 1.70 in Q2 2025.
- Free Cash Flow:NOK 4.0 billion.
- Net Debt:NOK 16.3 billion (adjusted net debt at NOK 22.8 billion), an increase from NOK 12.9 billion in Q1 2026 largely due to dividend distribution of approximately NOK 5.9 billion in May.
Segment Breakdown and Geographic Revenue Distribution
Norsk Hydro reports across five operational segments alongside corporate activities:
- Extrusions (approx. 40–45% of total gross sales): Manufactures tailored aluminum components and systems for building/construction, automotive, industrial, and electrical applications, alongside integrated recycling casthouses. Q2 2026 adjusted EBITDA reached NOK 1,463 million, supported by robust recycling margins and lower fixed costs.
- Aluminium Metal (approx. 25–30% of total revenue):Operates primary smelters producing extrusion ingots, foundry alloys, and sheet ingots.Adjusted EBITDA surged to NOK 6,421 million (up from NOK 2,423 million in Q2 2025) on realized metal prices of USD 3,268/mt and higher duty-paid premiums.
- Bauxite & Alumina (approx. 15–18% of total revenue): Operates the Paragominas bauxite mine and Alunorte alumina refinery in Brazil. Adjusted EBITDA declined to NOK 522 million (down from NOK 1,521 million in Q2 2025) due to lower alumina prices and Brazilian Real appreciation against USD.
- Metal Markets (approx. 10–12% of total revenue): Manages global trading, physical metal sourcing, hedging, and recycling casthouses. Adjusted EBITDA stood at NOK 32 million.
- Energy (approx. 3–5% of total revenue): Develops and operates hydroelectric power plants in Norway to secure internal smelter supply and trade merchant power. Adjusted EBITDA reached NOK 499 million, halved YoY due to lower reservoir levels and adverse price differentials.
Geographic Revenue Breakdown & Development:
- Europe (approx. 60–65%): Hydro’s primary market. European extrusion demand remained muted with a minor YoY rebound (+0.4%), led by commercial construction stabilization and EV light-weighting demand.
- North America (approx. 20–25%): Extrusions demand remained flat YoY; weakness persisted in automotive and trailer builds, but electrical infrastructure and recycling margins remained exceptionally strong.
- Other Markets / Rest of World (approx. 15%): Brazil houses Hydro’s raw material base (Alunorte and Paragominas), while Asia-Pacific and South America constitute expanding trading destinations for secondary metal and value-added ingots.
Plant Closures, Outlook & Future Catalyst Analysis
Recent Closures and Capacity Adjustments:
- European Extrusions Optimization:Following restructuring plans to address weak downstream demand and optimize unit production costs, Hydro completed the closure of two extrusion facilities in the UK during Q2 2026, alongside ongoing rationalization at the Lucé site in France.
- Smelter Restart:In contrast to downstream streamlining, Hydro announced the strategic agreement to restart the Slovalco primary smelter in Slovakia (75,000 tonnes capacity) starting July 1, 2026, rebuilding European primary supply.
Q3 2026 Guidance & Key Catalysts:
- Aluminium Metal:Realized pricing remains resilient with 62% of Q3 production hedged. However, seasonally lower volumes and upward pressure on carbon/energy costs will moderately squeeze margins.
- Bauxite & Alumina: Expected improvements in sales volume and a modest recovery in global alumina index prices.
- Extrusions:Volume growth is projected relative to Q3 2025, driven by seasonal demand and resilient recycling operations in North America.
- Long-term Outlook:Full-year 2026 capital expenditure is targeted at NOK 13.5 billion (NOK 9.0 billion sustaining, NOK 4.5 billion growth/decarbonization). The company continues to advance low-carbon products (Hydro CIRCAL and REDUXA) to capture green product premiums.
Three-Month Stock Price Performance and Drivers
Over the past three months (June to early September 2026), Norsk Hydro’s share price on the Oslo Børs (OSE: NHY) traded between NOK 85 and NOK 95, trading around NOK 93.9 to NOK 94.4 in early September.
- June 2026 (Pullback & Geopolitical Relief): LME aluminum prices pulled back from peak levels (dropping from over USD 3,500/mt toward USD 3,100/mt) due to the easing of Middle East shipping constraints, weighing temporarily on stock momentum.
- July 2026 (Earnings Boost):The stock rebounded following the Q2 2026 earnings beat on July 22, supported by strong EBITDA generation (NOK 8.92 billion), robust free cash flow, and the positive reception of the Slovalco restart.
- August – September 2026 (Consolidation): The stock maintained its upward trend toward NOK 94, buoyed by tight global primary aluminum inventories, ongoing European premium support, and a steady operational ramp-up at Norwegian smelters despite minor power price headwinds.
Sources
- https://www.hydro.com/en/global/media/news/2026/hydros-second-quarter-2026-operational-strength-delivering-solid-results/
- https://newsweb.oslobors.no/message/651604
- https://live.euronext.com/en/product/equities/NO0005052605-XOSL
- https://www.investing.com/news/company-news/hydro-q2-2026-slides-metal-segment-lifts-results-despite-volatility-93CH-4804789
Back to Norsk Hydro