
Latest Quarterly Earnings Summary
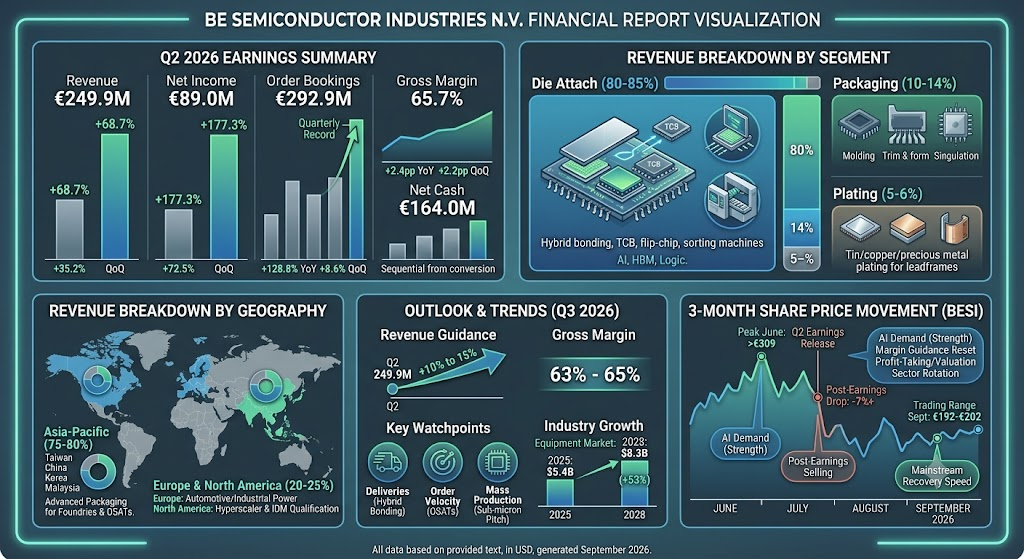
BE Semiconductor Industries N.V.(Besi)reported its Q2 2026 results on July 23, 2026, delivering substantial top-line and bottom-line expansion driven by high demand for artificial intelligence packaging systems:
- Revenue:€249.9 million, rising 68.7% YoY and 35.2% QoQ.
- Net Income:€89.0 million, an increase of 177.3% YoY and 72.5% QoQ.
- Order Bookings:€292.9 million, up 128.8% YoY and 8.6% QoQ, establishing a quarterly record driven by data center, photonics, and AI power management applications.
- Gross Margin:65.7%, up 2.4 percentage points YoY and 2.2 percentage points QoQ, supported by favorable product mix and operational leverage.
- Net Cash Position:€164.0 million as of June 30, 2026, increasing 58.8% sequentially following positive operating cash flow and the conversion of €175 million convertible notes.
Revenue Breakdown by Segment and Geography
Official Product Segments
Besi operates primarily in the development and manufacture of semiconductor assembly equipment across three main product lines:
- Die Attach(representing ~80-85% of total revenue): The core growth driver. It includes advanced hybrid bonding systems, thermo-compression bonding(TCB), flip-chip bonders, and die sorting machinery utilized in high-density advanced packaging for AI accelerators, high-bandwidth memory(HBM), and logic chiplets.
- Packaging(representing ~10-14% of total revenue):Covers molding, trim & form, and singulation systems designed to encapsulate integrated circuits into protective plastic packages.
- Plating(representing ~5-6% of total revenue): Provides tin, copper, and precious metal plating equipment used on semiconductor leadframes and substrates.
Geographic Distribution and Developments
- Asia-Pacific(representing ~75-80% of total revenue): The primary market, driven by leading foundries and outsourced semiconductor assembly and test(OSAT)facilities in Taiwan, China, South Korea, and Malaysia expanding advanced packaging lines for AI chips.
- Europe & North America(representing ~20-25% of total revenue): European demand is anchored in automotive and industrial power semiconductor applications, while North American revenue is propelled by direct equipment qualification from hyperscale compute designers and IDMs.
Quarter Dynamics, Next Quarter Watchpoints, and Outlook
Q2 Dynamics
- Operating leverage improved significantly as baseline operating expenses decreased to 18.9% of revenue compared to 30.0% in Q2 2025.
- Customer adoption of hybrid bonding expanded from 15 accounts at the end of 2025 to 21 accounts by the end of Q2 2026, broadening across logic, memory, and co-packaged optics(CPO)use cases.
Q3 2026 Guidance & Watchpoints
- Revenue Guidance:Expected to increase 10% to 15% sequentially relative to the €249.9 million reported in Q2 2026.
- Gross Margin Guidance:Projected between 63% and 65%, moderating slightly from 65.7% due to product mix shifts.
- Operating Expenses:Forecasted to remain flat to up 5% QoQ compared to €55.3 million in Q2 2026, primarily from ongoing R&D expenditures.
- Watchpoints: Delivery lead times for hybrid bonding units, order conversion velocity among tier-one OSATs, and customer progress transitioning sub-micron pitch packaging into high-volume manufacturing.
Future Outlook
According to industry research incorporated in company disclosures, the semiconductor assembly equipment market is forecast to expand from $5.4 billion in 2025 to $8.3 billion by 2028, representing a 53% increase, bolstered by AI server architectures and advanced node roadmaps.
Three-Month Share Price Movement and Market Drivers
Price Trajectory
- BESI(Euronext Amsterdam: BESI)traded near its 52-week peak above €309 in mid-June 2026, before trending downward to €227 following the Q2 earnings release in late July, and hovering around €192 to €202 by early September 2026.
Market Drivers
- Profit-Taking and Lofty Expectations: Despite record order bookings of €292.9 million, the stock encountered immediate post-earnings selling(dropping over 7% post-report)as elevated valuation multiples left little room for a slight margin guidance reset for Q3 2026.
- Broad Semiconductor Sector Rotation: Mid-2026 profit-taking across European chip capital equipment names(such as ASML and Besi)weighed on share performance amid macro caution and export regulation reviews.
- Mainstream Market Recovery Velocity: While leading-edge AI applications displayed strong order momentum, standard automotive and industrial end-markets exhibited a more measured recovery slope, tempering near-term consensus EPS adjustments.
Information Sources
- https://www.besi.com/investor-relations/press-releases/details/be-semiconductor-industries-nv-announces-q2-26-and-h1-26-results/
- https://www.investing.com/news/company-news/besi-q2-2026-slides-ai-demand-drives-record-orders-stock-dips-93CH-4809526
- https://www.globenewswire.com/news-release/2026/07/23/3331898/0/en/be-semiconductor-industries-n-v-announces-q2-26-and-h1-26-results.html
- https://live.euronext.com/en/product/equities/NL0012866412-XAMS/market-information
- https://www.tipranks.com/stocks/nl:besi
Back to BE Semiconductor