
Market Position and Market Share
Tenaris S.A. is the world’s largest manufacturer and supplier of seamless steel pipes and related tubular solutions, specifically dominating the Oil Country Tubular Goods(OCTG) segment.
- Global Ranking: Ranked #1 globally in seamless OCTG production and premium threaded connections.
- Market Share: In the high-barrier, premium OCTG market(tubulars designed for deepwater, high-pressure/high-temperature HPHT, and unconventional shale wells), Tenaris holds an estimated 30% to 35% global market share. Across the broader overall OCTG volume market(including standard welded and seamless pipes), its global volume share is estimated between 15% and 20%. In the Americas(notably the United States, Argentina, and Mexico), its market presence is dominant, often exceeding 40% of the premium tubular market due to strong domestic manufacturing footprints.
- Scale: Annual consolidated revenues consistently sit between $12 billion and $15 billion, giving it more than double the revenue scale of its closest dedicated pure-play competitor.
Supply Chain Analysis and Key Suppliers
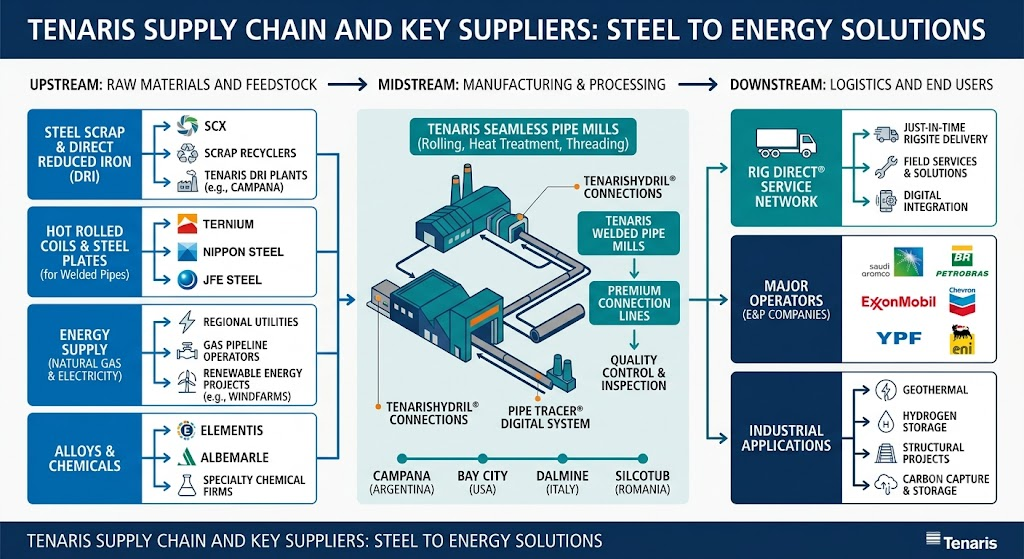
Tenaris operates an operationally integrated “steel-to-well” supply chain designed to minimize scrap loss, capture value added, and deliver directly to drill sites.
- Upstream(Raw Materials and Energy):
- Feedstock & Scrap: Tenaris utilizes Electric Arc Furnaces(EAF) for a large portion of its steelmaking, sourcing steel scrap, Direct Reduced Iron(DRI), and pig iron. It partially integrates DRI production(such as in Campana, Argentina) and purchases merchant scrap from major metal recycling aggregators.
- Steel Billets & Slabs: While largely self-sufficient in steel billets for seamless pipe extrusion, Tenaris procures external hot-rolled coils(HRC) and steel plates for its welded pipe lines from primary steelmakers such as Ternium(an affiliate under Techint Group) and Nippon Steel.
- Energy: Seamless pipe manufacturing is energy-intensive. Tenaris secures high-voltage power agreements and natural gas contracts from regional utilities and pipeline operators, while increasingly investing in proprietary renewable assets(e.g., wind farms in Argentina) to mitigate power price volatility.
- Midstream Manufacturing:
- Tenaris operates specialized seamless rolling mills, heat treatment plants, threading lines, and inspection centers globally(key hubs located in the US, Mexico, Argentina, Italy, Romania, and Saudi Arabia).
- Downstream(Logistics and Direct Customer Integration):
- The Rig Direct® Model: Instead of relying solely on third-party OCTG stocking distributors, Tenaris delivers casing and tubing directly to the drilling rig on a just-in-time basis.
- Key End-Users: Exploration and production(E&P) majors, national oil companies(NOCs), and independent operators, including Saudi Aramco, Petrobras, ExxonMobil, Chevron, YPF, and Eni.
Competitor Analysis: Technical and Financial Comparison
The primary global competitors in the premium OCTG and seamless pipe space include Vallourec(France), TMK Group(Russia), and Japanese steel conglomerates such as Nippon Steel Corporation and JFE Steel.
- Technical Comparison:
- Proprietary Premium Connections: Tenaris’s flagship TenarisHydril(Wedge Series, Blue® series) competes directly with Vallourec’s VAM® family and Nippon Steel’s proprietary joints. Both TenarisHydril and VAM represent the industry benchmark for gas-tight seals in horizontal shale wells and deepwater environments.
- Metallurgy & Extreme Well Conditions: Vallourec and Nippon Steel maintain high technical competence in extreme corrosion-resistant alloys(CRA) and high-nickel alloys for ultra-sour gas fields. Tenaris counters with deep metallurgic formulation capabilities and an expansive suite of dopeless connection technologies, eliminating the need for pipe dope(thread compound), which reduces rig environmental footprint and running time.
- Supply Chain Integration: Tenaris holds a distinct technological and operational edge over Asian and European peers through digital integration(PipeTracer®) and the Rig Direct service network, reducing pipe failure rates and working capital requirements for operators.
- Financial Comparison:
- Revenue & Operational Scale: Tenaris generated ~$12B–$14B in revenue, whereas Vallourec generates ~$4B–$4.5B. Japanese mills maintain larger overall revenues but their pipe segments form only a modest fraction of conglomerate operations.
- Margins & Profitability: Tenaris consistently delivers superior operating and EBITDA margins(historically 20%–35% during upcycles) compared to competitors. Vallourec, which completed significant financial and asset restructurings, typically achieves 15%–20% EBITDA margins.
- Balance Sheet Strength: Tenaris maintains an exceptionally strong balance sheet with a net cash position and negligible gross debt.In contrast, historical peers like Vallourec have had to undergo major debt-to-equity restructuring to resolve leverage, though Vallourec now operates with positive net cash.
Information Sources
- https://ir.tenaris.com
- https://www.fortunebusinessinsights.com/industry-reports/oil-country-tubular-goods-market-101396
- https://www.alpha-sense.com/earnings/ts/
- https://pitchbook.com/profiles/company/31685-23
- https://companiesmarketcap.com/vallourec/revenue/
- https://www.nasdaq.com/press-release/vallourec-fourth-quarter-and-full-year-2024-results-2025-02-27
Back to Tenaris