
Latest Financial Results Summary (H1 2026)
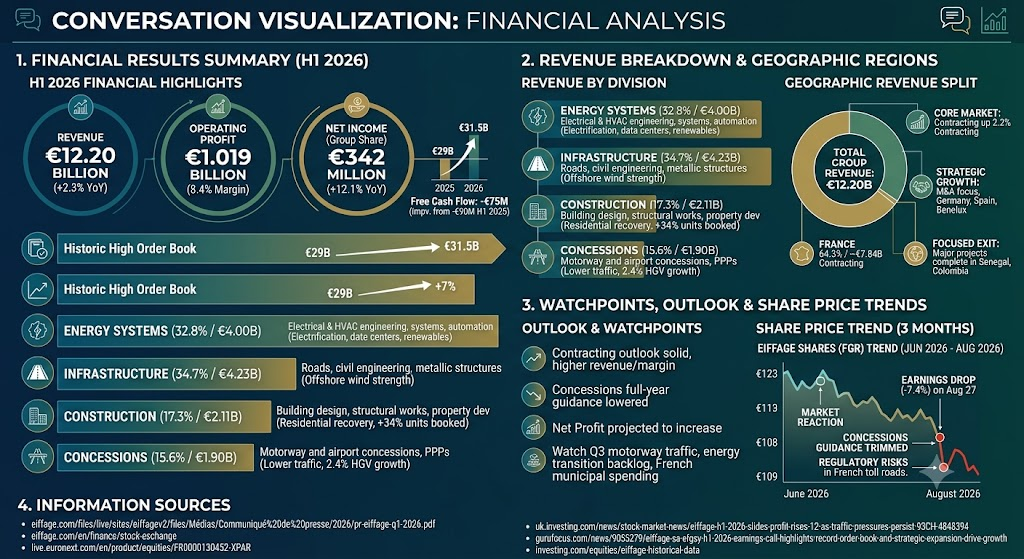
Eiffage released its financial results for the first half of 2026 on August 26, 2026, delivering steady operational growth driven by its contracting branches:
- Revenue:Consolidated revenue reached €12.20 billion, an increase of 2.3% on an actual basis (+1.1% on a like-for-like/lfl basis) compared to H1 2025.
- Operating Profit on Ordinary Activities:Rose 2.0% year-over-year to €1.019 billion, keeping the operating margin stable at 8.4%.
- Net Income (Group Share):Rose 12.1% to €342 million, up from €305 million in H1 2025.
- Contracting Operating Profit:Grew 11.6% to €269 million, expanding the operating margin by 20 basis points to 2.6%.
- Free Cash Flow:Stood at negative €75 million, reflecting standard first-half seasonal working capital requirements but showing improvement over negative €90 million in H1 2025.
- Order Book:Reached a historic high of €31.5 billion, up 7% year-over-year, representing more than 16 months of contracting activity.
Revenue Breakdown by Division and Geographic Region
Division Breakdown (Official Group Reporting)
Eiffage categorizes its operations into two main branches: Contracting (comprising Construction, Infrastructure, and Energy Systems) and Concessions.Total H1 2026 consolidated revenue was €12.20 billion:
- Energy Systems (32.8% of Total Revenue / €4.00 billion): Provides electrical, mechanical, and HVAC engineering, system integration, automation, and telecommunications. Revenue expanded 4.8% (+2.0% lfl), driven by electrification, industrial automation, and renewable infrastructure, while segment operating margin expanded 30 basis points to 5.2%.
- Infrastructure (34.7% of Total Revenue / €4.23 billion):Encompasses road building, civil engineering, earthmoving, and metallic structures. Revenue held flat (+0.0% actual, -1.3% lfl), where strong momentum in offshore wind projects at Eiffage Métal (+46.7%) offset declines in road works (-4.2%) affected by French municipal election cycles.
- Construction (17.3% of Total Revenue / €2.11 billion): Covers building design, structural works, renovation, property development, and off-site modular solutions. Revenue grew 5.0% (actual and lfl) with residential bookings recovering to 1,224 units (up from 916 units in H1 2025).
- Concessions (15.6% of Total Revenue / €1.90 billion):Manages motorway concessions (notably APRR, AREA, and A79 Aliaé), airport assets (Lille, Toulouse), and public-private partnerships (PPP). Revenue was down 0.4% (+0.5% lfl) due to a 2.5% decrease in light vehicle motorway traffic, though heavy goods vehicle (HGV) traffic increased 2.4%.
Geographic Revenue Breakdown
- France (64.3% of Group Revenue / ~€7.84 billion): France remains the core market. Contracting in France reached €5.94 billion (+2.2%), while concessions generated the majority of their toll revenues domestically.
- Europe Excluding France (34.4% of Group Revenue / €4.20 billion in Contracting):European contracting grew 8.0% (+3.6% lfl).Expansion was led by Germany, Spain, Belgium, Luxembourg, and the Netherlands, alongside targeted acquisitions such as HSM and Bartz Group.
- Outside Europe (1.3% of Group Revenue / €0.16 billion): International contracting outside Europe saw revenue drop sharply to €118 million in Infrastructure as planned project completions occurred in Senegal and Colombia (Puerto Antioquia), reflecting the group’s refocusing on core European markets.
Recent Operational Changes, Next Quarter Watchpoints, and Outlook
Operational Changes This Period
- Toll Road Softness vs. Freight Resilience:Concession operating income declined to €822 million due to lower domestic consumer travel and fuel price sensitivity, but commercial logistics traffic remained healthy (+2.4%).
- Strategic Rebalancing & M&A: The group deployed €204 million into external growth during H1 2026, targeting European electrical engineering and data center support firms.
- Strengthened Stake in Infrastructure Assets: Eiffage bolstered recurring concession revenue via its 29.4% stake in Getlink, recognizing €34 million in equity-accounted profit and receiving €129 million in dividends.
Key Watchpoints for the Coming Quarter
- Concession Traffic Trends: Monitoring whether French motorway traffic recovers during the peak Q3 summer holiday season to stabilize toll receipts.
- Energy Transition Backlog Conversion:Execution on high-value nuclear (EPR2) and renewable projects, plus the conversion rate of complex European data center proposals into signed contracts.
- French Municipal & Public Spending: Tracking whether public road maintenance tender volumes rebound after post-electoral delays.
Future Outlook
- Contracting Outlook: Eiffage reaffirmed full-year expectations for higher revenue and operating margins, led by 9% order book growth in Energy Systems and steady margins across Construction and Civil Engineering.
- Concessions Revision: Full-year concession revenue and operating results have been revised slightly downward from original guidance to reflect persistent light-vehicle volume softness.
- Net Profit:Group share of net profit is projected to increase for the full year 2026, underpinned by contracting margin expansion and lower debt service costs.
Three-Month Share Price Trend and Market Drivers
- Price Movement:Over the last three months (early June 2026 to late August/early September 2026), Eiffage shares (Euronext Paris: FGR) trended lower.After trading around €123–€131 in June 2026, the stock slid to approximately €108.80–€109.70 as of late August 2026, reflecting a three-month decline of roughly 11% to 13%.
- Earnings Reaction Drop:On August 27, 2026 (the session following the earnings release), the stock dropped 7.4% from €117.50 to €108.80.
- Primary Market Drivers:
- Concessions Guidance Trim:While net profit beat expectations (+12.1%), investors focused on management lowering the full-year outlook for the concessions division from “slight increase” to “slightly lower than 2025” due to motorway traffic softness. Motorway concessions represent Eiffage’s highest-margin, cash-generative pillar.
- Broader French Infrastructure Discount: Continued European political and regulatory scrutiny surrounding French toll road operator taxation and concessions concessions timelines has pressured domestic infrastructure multiples.
- Subdued Residential Property Sector: Despite minor sequential volume increases, the real estate market in France remains sluggish, dampening short-term development sentiment.
Information Sources
- https://www.eiffage.com/files/live/sites/eiffagev2/files/M%C3%A9dias/Communiqu%C3%A9%20de%20presse/2026/pr-eiffage-q1-2026.pdf
- https://www.eiffage.com/en/finance/stock-exchange
- https://live.euronext.com/en/product/equities/FR0000130452-XPAR
- https://uk.investing.com/news/stock-market-news/eiffage-h1-2026-slides-profit-rises-12-as-traffic-pressures-persist-93CH-4848394
- https://www.gurufocus.com/news/9055279/eiffage-sa-efgsy-h1-2026-earnings-call-highlights-record-order-book-and-strategic-expansion-drive-growth
- https://www.investing.com/equities/eiffage-historical-data
Back to Eiffage